Is it still a good idea to invest in new-build property on the French Riviera? If so, which areas are the most attractive and where do property values remain strong? Which market segments should you consider, and what are their respective advantages? What budget should you set aside to buy a property? In this article, we tell you everything you need to know to make a successful purchase and treat yourself to a little corner in the sun.
The reputation of the French Riviera is already well established, as are the many advantages of its lifestyle offering: a mild Mediterranean climate that makes it a true open-air health retreat, legendary sunshine with more than 300 days of sun per year, and the remarkable beauty and diversity of its landscapes. From the spectacular Esterel Massif to a coastline alternating between white-sand beaches, secluded coves, bays and dramatic red cliffs plunging into the sea, complemented by lush and exotic vegetation, everything contributes to making this coastal strip — spanning the Var and Alpes-Maritimes departments and stretching broadly from Toulon to Menton — a territory both unique and emotionally captivating.
From its hilltop medieval villages with authentic Provençal charm to its renowned seaside resorts such as Sainte-Maxime, Saint-Raphaël and Saint-Tropez, as well as internationally renowned cities like Nice and Cannes, it is hardly surprising that the region attracts millions of visitors every year — and, above all, a substantial number of real estate investors from across the globe, many of whom are prepared to pay a premium to acquire a foothold in what is widely regarded as one of the most desirable destinations in the world.
THE FRENCH RIVIERA PROPERTY MARKET: DYNAMIC AND HIGHLY SEGMENTED
First and foremost: yes, investing in new-build real estate on the French Riviera remains highly attractive and continues to represent a genuine opportunity for discerning investors. It is one of the few French property markets that combines a unique set of fundamentals capable of sustaining both market momentum and long-term capital appreciation.
The Key Drivers Supporting the Market
The first factor is the chronic shortage of developable land. Between the coastline, the hilly topography and increasingly restrictive urban planning regulations, very little land remains available for construction. As a result, new developments are scarce, particularly in prime locations, which mechanically supports property prices.
Secondly, the region benefits from strong international demand. The French Riviera attracts affluent retirees, international executives drawn by the region’s dynamic economy and established technology hubs such as Sophia Antipolis and Valbonne, remote workers, second-home buyers, long-term wealth investors and a substantial base of high-net-worth foreign purchasers from the Middle East, Switzerland, Italy, the United Kingdom and Northern Europe. In certain markets such as Nice, foreign buyers can account for as much as one-third of transactions in some segments.
In addition, the strength of the local economy helps sustain a virtuous cycle. Contrary to popular belief, the French Riviera is not solely dependent on tourism. Its economy is considerably more diversified and resilient than often assumed, driven by key economic engines including the Sophia Antipolis technology cluster and its tens of thousands of highly qualified jobs, Nice Côte d’Azur International Airport, international congresses and events, the healthcare and research sectors, yachting and luxury industries, as well as the growth of premium remote working. The presence of major universities also contributes to demographic growth and sustained residential demand.
Finally, the declining pipeline of new residential developments is expected to create a structural supply shortage over the coming years. While the slowdown in France’s new-build market since 2023 has weakened volumes nationally, it is likely to generate future scarcity in high-demand areas, thereby supporting prices. On the French Riviera, this effect is expected to be even more pronounced given that supply was already historically constrained.
A Diverse and Segmented Market
Most people associate the French Riviera solely with the stretch between Cannes and Nice. In reality — although no universally accepted geographical definition exists — the region extends far beyond this area and, according to some interpretations, covers a much broader coastal strip ranging from Cassis to Menton.
Nevertheless, the Riviera property market remains highly segmented and heterogeneous. It is essential to distinguish between established prime residential areas offering strong wealth preservation, emerging districts undergoing significant transformation and the ultra-prime international luxury segment.
So, Var or Alpes-Maritimes? These two departments in southeastern France each offer specific advantages for real estate investment. La réponse dépendra donc de ses propres critères de recherche : sécurité patrimoniale, potentiel de plus-value, rendement, prestige, accessibilité et critères de vie personnelle. Examinons ces deux marchés aux caractéristiques différentes.
THE ALPES-MARITIMES: A MARKET THAT REMAINS AS “EXTRAORDINARY” AS EVER”
The Alpes-Maritimes is arguably the most international property market in France after Paris and one of the most exclusive and supply-constrained in Europe. Beyond its intrinsic advantages, its prestige has been firmly established since at least the mid-19th century, with the rise of tourism symbolised by the creation of the Promenade des Anglais in Nice.
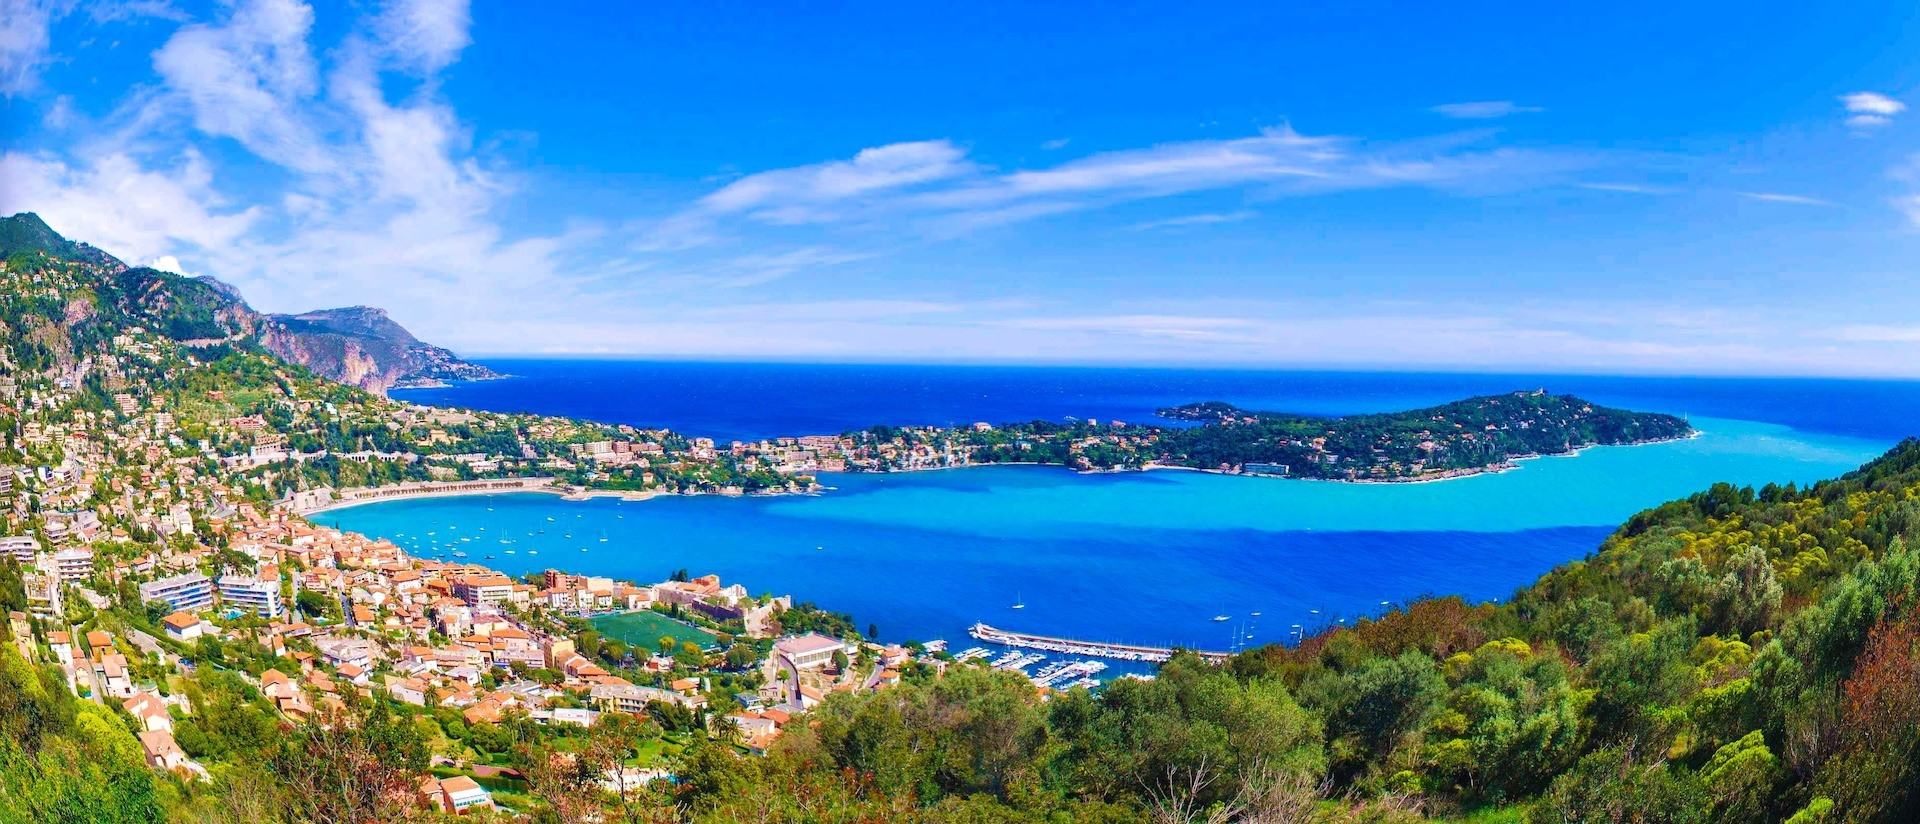
Property prices are among the highest in France, generally ranging from €5,000 to €9,000 per m2 for mid-range new-build developments, with significantly higher levels on the prime coastal market. Strong international demand means that the market is less dependent on the French domestic economic cycle. Combined with extreme land scarcity and a structurally undersupplied market, this continues to fuel upward price pressure, resulting in a substantial entry ticket for buyers.
Prices Continue to Rise Strongly
Despite the broader slowdown recently observed across France, price growth in the Riviera’s new-build market remains robust, particularly in the region’s most sought-after locations.
In Nice, recent estimates point toincreases ranging from 15% to 29% in the new-build sector, depending on neighbourhoods and market segments. This upward momentum has continued into 2025–2026, with additional growth estimated between 1% and 6% depending on the segment. While emerging districts with strong redevelopment potential — such as Nice East, Le Port, Saint-Roch, Riquier and Libération — are benefiting from infrastructure upgrades and ongoing gentrification, the city’s established prime residential districts including Mont Boron, Cimiez, Carré d’Or, Fabron and the Promenade des Anglais continue to represent secure long-term value plays, offering slightly lower but highly resilient appreciation potential.
The same is true in Antibes, where prices have risen 13% over the past five years, despite a slight recent decline. New construction remains scarce there and offers a very good balance thanks to its appeal to the population of executives who work in Sophia-Antipolis.
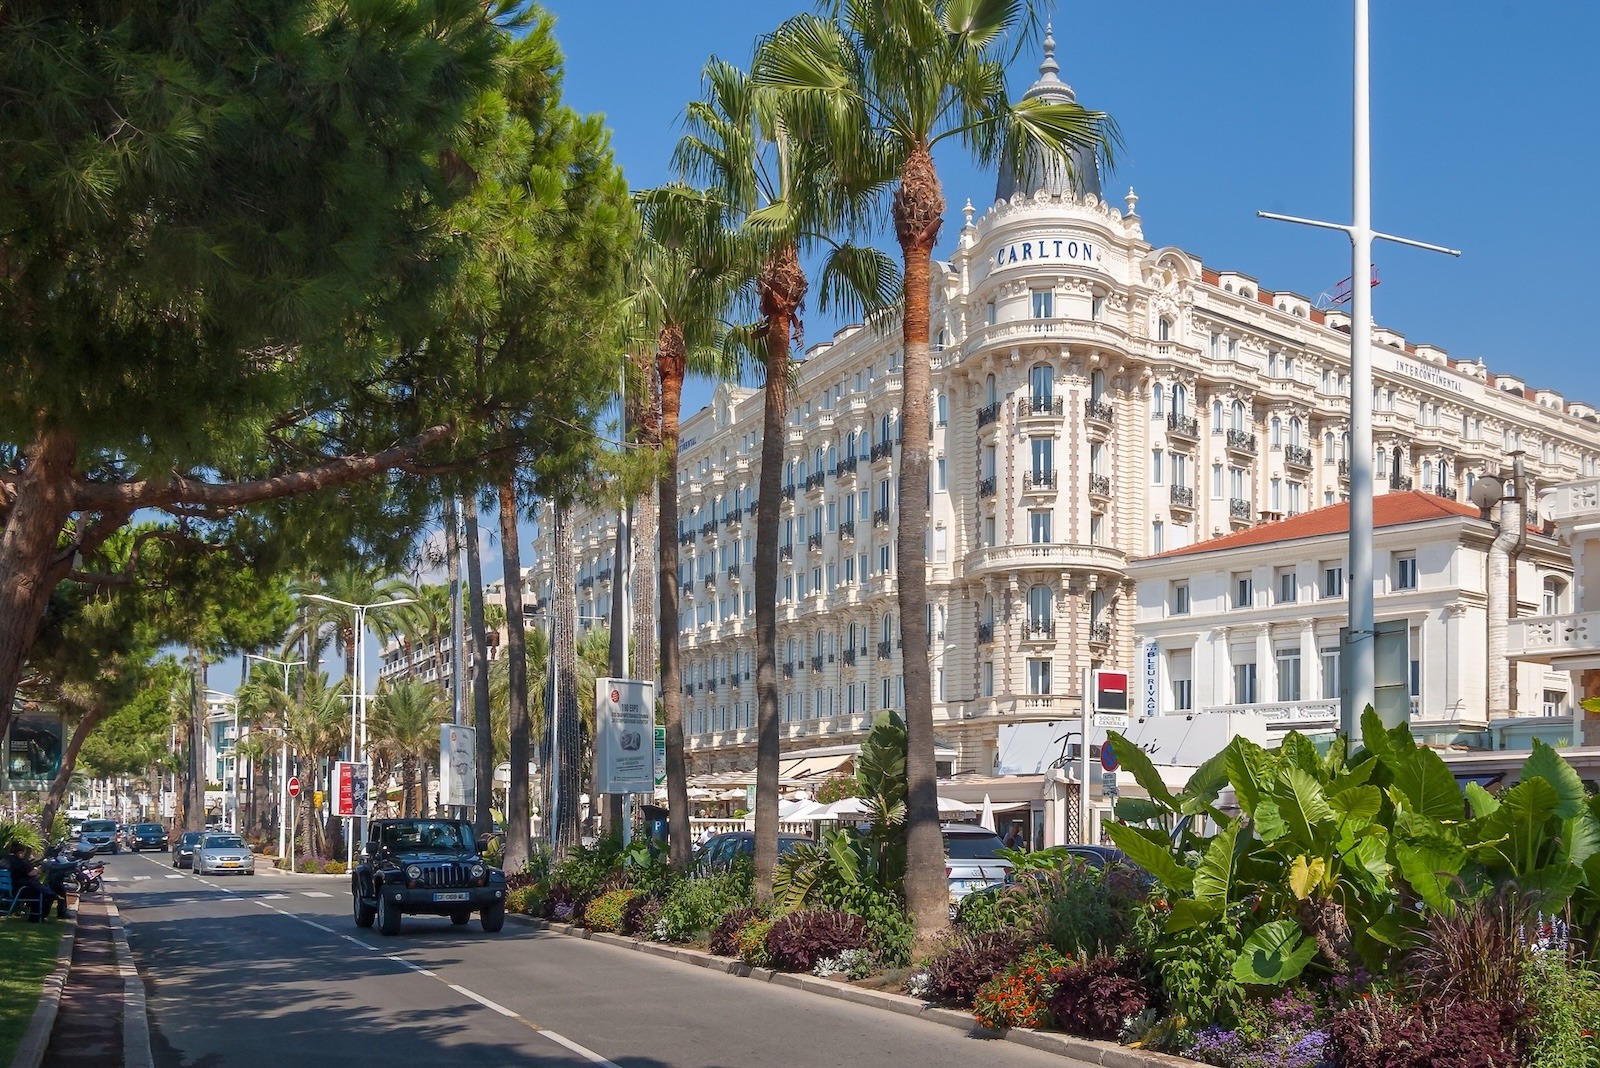
In Cannes, while the broader market has become more stable and traditional buy-to-let investments tend to offer lower yields, the prime and luxury segments continue to perform particularly well, notably due to strong demand for premium seasonal rentals and high-end second homes from international clientele.

Beausoleil should also be highlighted as a highly sought-after market benefiting from a spillover effect linked to its immediate proximity to Monaco. The area continues to enjoy significant growth potential driven by Monaco-based professionals unable to secure housing within the Principality itself due to its chronic lack of residential supply.
The same favorable conditions apply to Roquebrune Cap-Martin, one of the most attractive and resilient markets between Nice and Menton. Located just a stone’s throw from Monaco, this small town — with its superb beaches and medieval village — has seen real estate prices rise by more than 20% over the past five years (2020–2025).
New developments are rare here, and those that are launched offer all the right conditions for potential appreciation, due to the scarcity of land, strong rental demand, the exceptional living environment, and spectacular ocean views, such as the new Coeur de Carnolès residence, which is set to open in 2029 in a brand-new eco-neighborhood overlooking the Mediterranean.
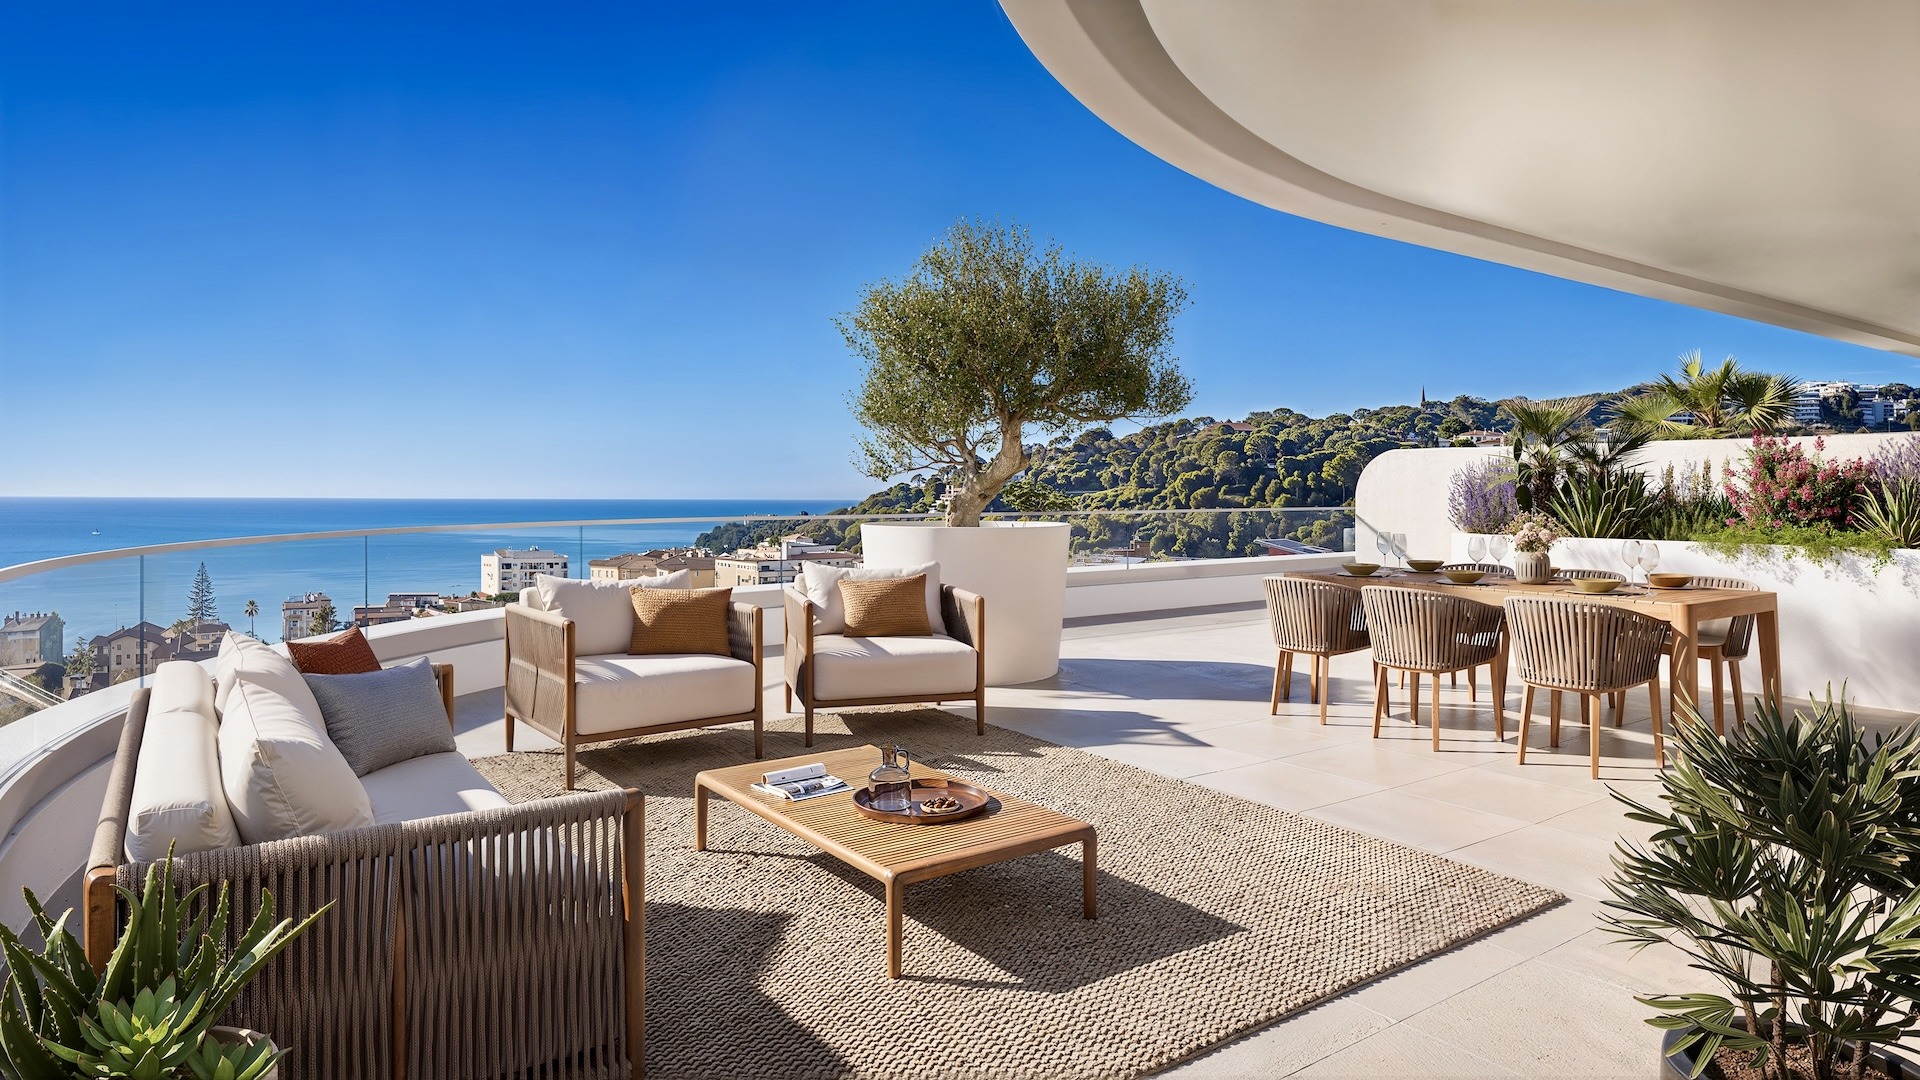
However, we should not overlook markets that are less “premium” and positioned in the entry-level or mid-range segments.
Towns such as Cagnes-sur-Mer and Le Cannet, as well as Vallauris and Saint-Laurent-du-Var, offer attractive options in new-construction real estate for mid-range budgets, with properties that provide good market depth and are priced more affordably, suggesting reasonable appreciation potential.

Who Is Buying ?
In the mid-market residential segment, buyers are primarily local professionals, executives, families, remote workers relocating from Paris or Lyon, and buy-to-let investors. The most popular areas include Nice East, Le Cannet, Cagnes-sur-Mer, Vallauris and selected parts of Antibes.
In the upper mid-range and high-end segment, buyers typically consist of affluent professionals, liberal professions, expatriates and semi-resident foreign purchasers. Demand is concentrated in districts such as Cimiez and Fabron in Nice, La Californie in Cannes, Antibes/Juan-les-Pins and Beaulieu-sur-Mer.
Finally, in the prestige, luxury and ultra-prime segment, buyers are predominantly ultra-high-net-worth individuals and long-term wealth investors who are less sensitive to interest-rate fluctuations. Their focus remains concentrated on a handful of globally recognised addresses, including La Croisette in Cannes, Saint-Jean-Cap-Ferrat, Villefranche-sur-Mer, Cap d’Antibes, Èze and Cap-d’Ail.
THE VAR : A STRONGER POTENTIAL VALUE-TO-PRICE RATIO
The Var offers a highly compelling alternative to the Alpes-Maritimes, with a stronger potential value-to-price ratio, particularly for investors whose strategy is not solely focused on long-term trophy asset preservation. It is also a département that encompasses several markedly different real estate markets: a premium coastal market, more accessible “spillover” cities, residential areas catering to working professionals, as well as an inland hinterland that remains relatively affordable.
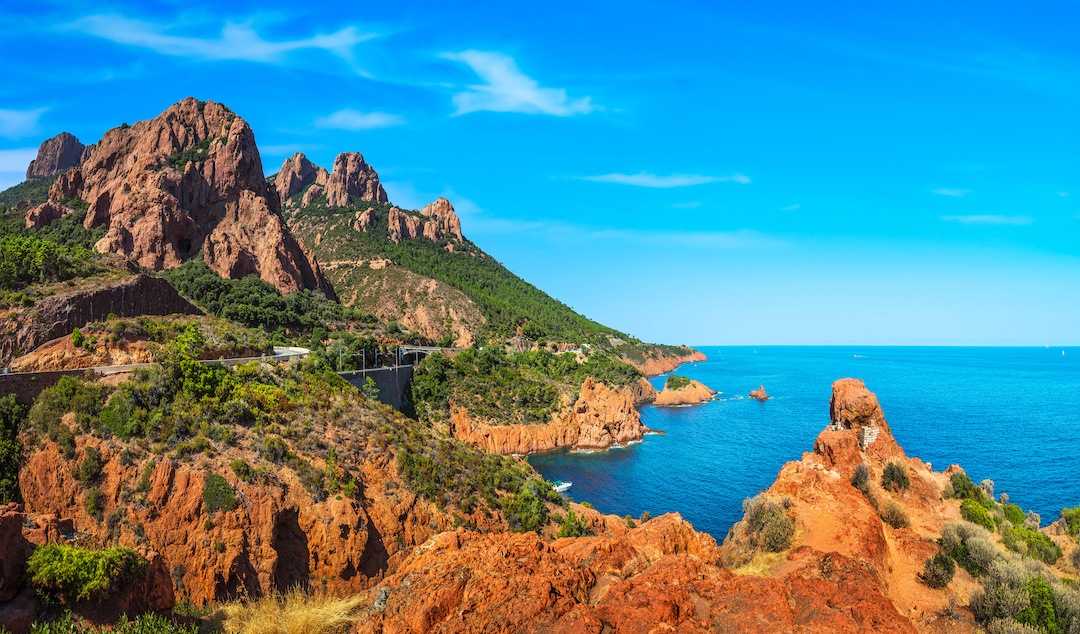
Often regarded as one of France’s most beautiful départements, thanks to its unspoiled natural environment and exceptional landscapes, the Var benefits from a spillover effect driven by buyers who now consider prices in Nice, Cannes, or Antibes excessively high. This trend continues to support demand in cities such as Toulon, Hyères, Saint-Raphaël, Sainte-Maxime, Grimaud, Fréjus, Six-Fours-les-Plages, Sanary-sur-Mer, La Londe-les-Maures, and Le Lavandou.
Scarce New-Build Supply Along the Coastline
Offering many of the same advantages as the Alpes-Maritimes—with the added appeal of a more rugged, preserved natural environment—the Var remains one of the strongest drivers of the French property market today.
Whether in the Gulf of Saint-Tropez, notably in Grimaud and Sainte-Maxime, or further east around Fréjus and Saint-Raphaël, the same structural fundamentals continue to fuel a supply-constrained market: limited land availability, stringent urban planning regulations, strict Coastal Law restrictions (Loi Littoral), resistance to densification, and sustained international demand.
The result is clear: new-build residential stock remains scarce, particularly in close proximity to the waterfront.
In Sainte-Maxime, therefore, the property market remains very buoyant, driven by a structural shortage. Average property prices there have risen by 20 to 40% overall over five years (2020–2025), with seafront properties, such as those in La Nartelle, Le Sémaphore or the Croisette neighbourhood, outperforming the market by 10 to 20 percentage points (ranging from +28.9% according to PAP to +35% according to Le Figaro Immobilier). A sea view also justifies a premium.
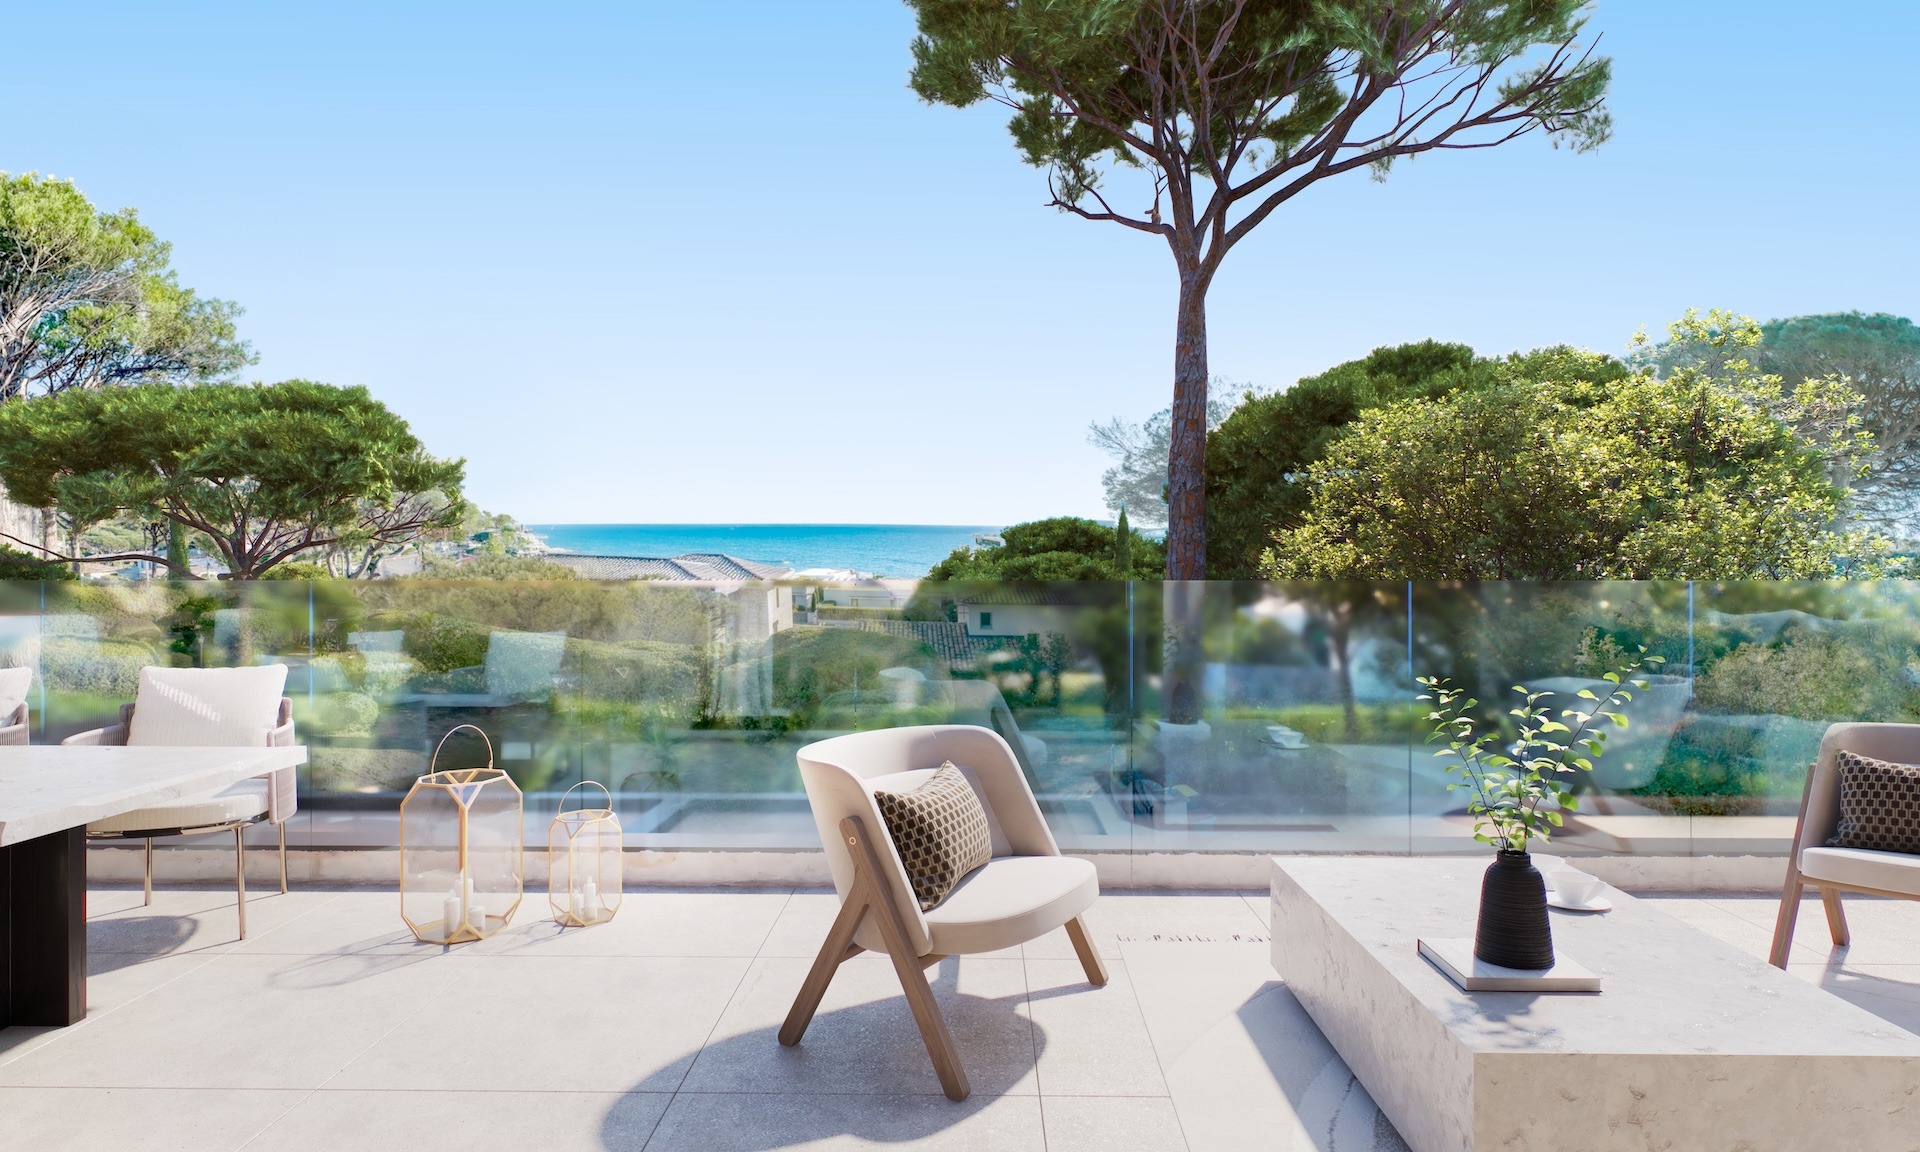
While the Var property market is less dependent on ultra-high-net-worth foreign buyers—which means less of the “global safe haven” protection enjoyed by certain Côte d’Azur trophy markets, but also reduced speculative pressure—it is also a more fundamentally residential market: a greater share of primary residences, affluent French retirees, senior executives, and semi-resident owners contribute to a healthier, more stable, and more liquid marketplace.
Highly Differentiated Real Estate Micro-Markets
The Var real estate market is considerably more diverse than that of the Alpes-Maritimes. As such, the most attractive locations vary significantly depending on whether an investor prioritises long-term capital preservation, capital appreciation potential, or rental yield performance.
Looking from west to east, among the towns that are holding up very well or continuing to grow, Sanary-sur-Mer and Bandol stand out as very strong real estate markets. Their value has risen in recent years, and they are now highly sought after by affluent buyers. Very strong demand and the scarcity of available properties have driven prices up, often exceeding €6,500 to €7,000 per square meter. While the potential for appreciation is lower there because prices are already high, these areas remain attractive due to their excellent ability to hold their value.
More accessible than Cassis, Bandol is a renowned upmarket seaside resort with shops open all year round, attracting a high-income clientele. Prices there are nevertheless already quite high (€6,700 per m² on average) in a market that remains relatively liquid.
Sanary-sur-Mer is the rising star of this stretch of coastline, having seen a huge boost to its reputation over the last ten years, largely thanks to its vibrant town centre. It attracts a clientele of families and affluent retirees, with strong demand for second homes, pushing the average price of new-build property to around €6,500 per m².
With its sizeable year-round population, the nearby Île des Embiez, the Lônes district and the hamlet of Le Brusc, Six-Fours-les-Plagesoffers many advantages and excellent value for money, with average prices for new-build properties ranging from around €5,100 to €5,400/m2, making it an ideal market for a family home or a main residence.
Finally, La Seyne-sur-Mer is undergoing urban regeneration but remains, without doubt, the most affordable market on the Côte d’Azur. Apartments there can be found at prices ranging from €3,300 per square metre to €4,700/m2, which can offer good potential for rental returns and capital appreciation, particularly on the beaches of Les Sablettes, Mar Vivo and Tamaris.
Of all the cities along the French Mediterranean coast, Toulon is probably the most underrated. Yet it is brimming with assets: a very stable military base, a university, a genuine urban regeneration drive in recent years, the influx of a higher-income population, prices that remain reasonable, and a significant improvement in its image thanks to major development projects that will transform the face of this city, which has long suffered from a poor reputation. Toulon is a bit like ‘Nice 15–20 years ago’ on a smaller scale: urban regeneration, major development projects, an improved image, the arrival of new residents and prices that are still discounted. This is where the biggest ‘turnaround story’ of the next twenty years could unfold.
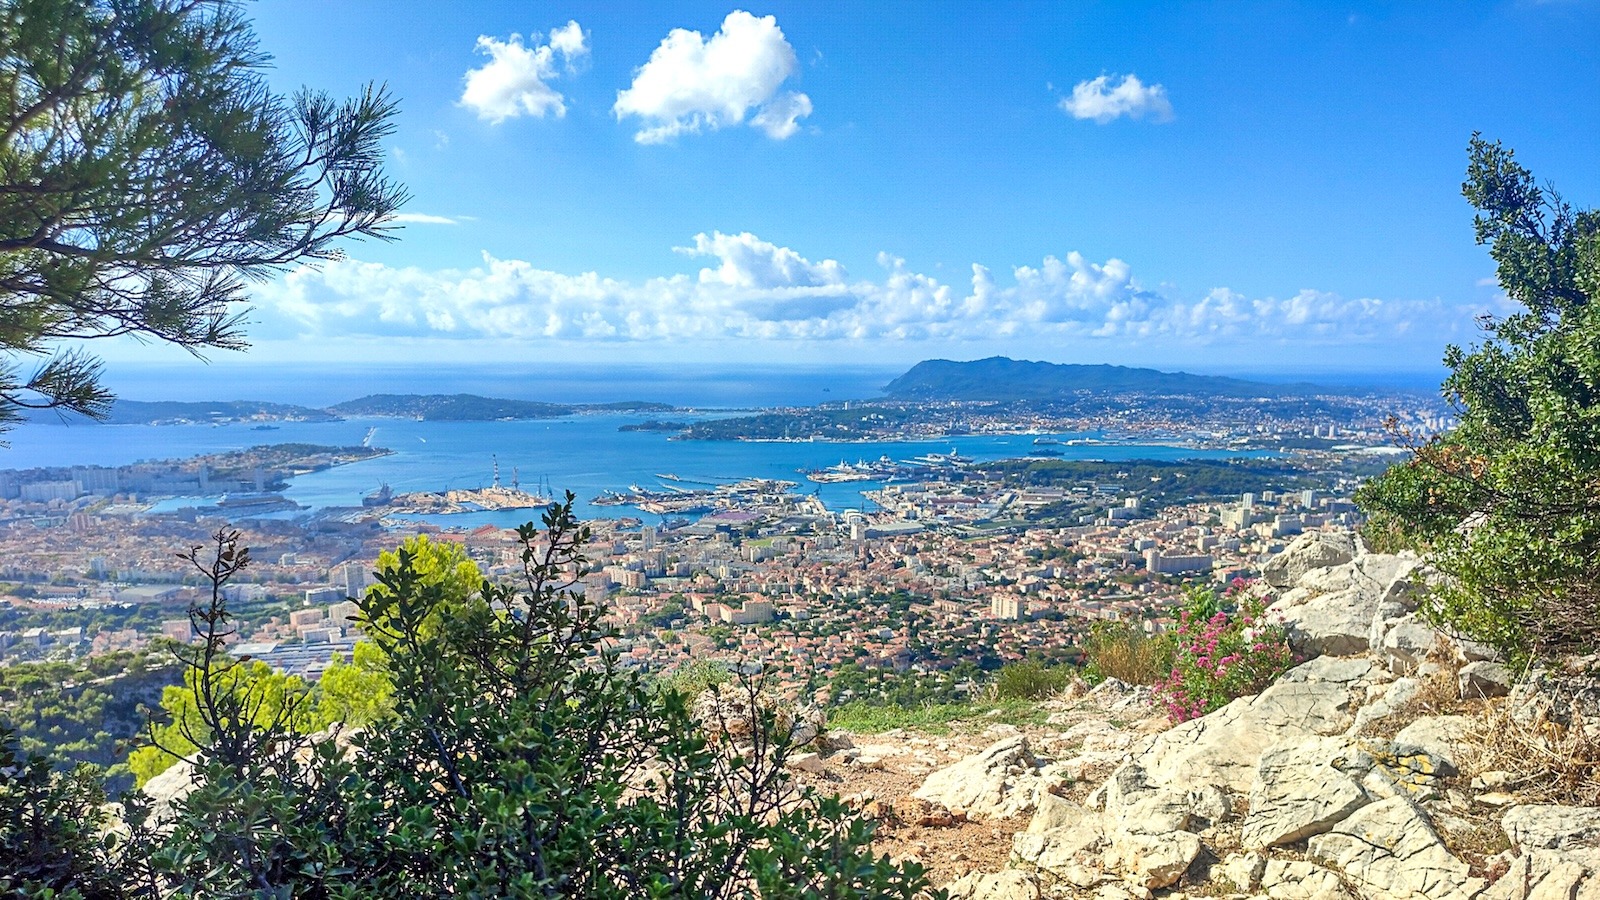
Districts such as Le Mourillon, Cap Brun, La Serinette, and selected parts of the renovated city centre now offer attractive appreciation potential over the next ten years, while often delivering stronger rental yields than Nice or Cannes—particularly in the highly sought-after mid-market two- and three-bedroom apartment segment.
Located close to Toulon yet representing a fundamentally different market profile, Hyères is widely regarded as a defensive, wealth-preservation residential market. This premium lifestyle-driven segment remains highly sought after by affluent retirees, second-home buyers, and a more discreet international clientele.
Its core strengths—such as the Îles d’Or archipelago, exceptional quality of life, low crime rates, and remarkable natural heritage—make it a more expensive but also more resilient market than Toulon, albeit one that tends to be less liquid outside the peak seasonal cycle.
Among the coastal markets demonstrating continued resilience and appreciation, Sanary-sur-Merand Bandol stand out as particularly robust real estate markets. Their desirability has risen significantly in recent years, making them highly sought after by affluent domestic buyers. Strong demand combined with limited supply has driven prices above €6,500 to €7,000 per square metre in many cases.
While upside potential may be comparatively more limited given current pricing levels, these markets remain attractive due to their excellent value retention characteristics.
Further towards Saint-Tropez, Le Lavandou and Bormes-les-Mimosas have also firmly repositioned themselves within the premium segment, experiencing a notable market upgrade over recent years. Benefiting from premium tourism, extreme land scarcity, and sustained demand for second homes, they have posted some of the strongest recent price growth within the Var.
The Fréjus/Saint-Raphaël conurbation represents a large and highly liquid residential market offering an attractive balance between climate appeal, tourism fundamentals, and market depth. As such, it remains particularly popular with retirees, while also benefiting from rapid motorway access to Cannes and Nice.
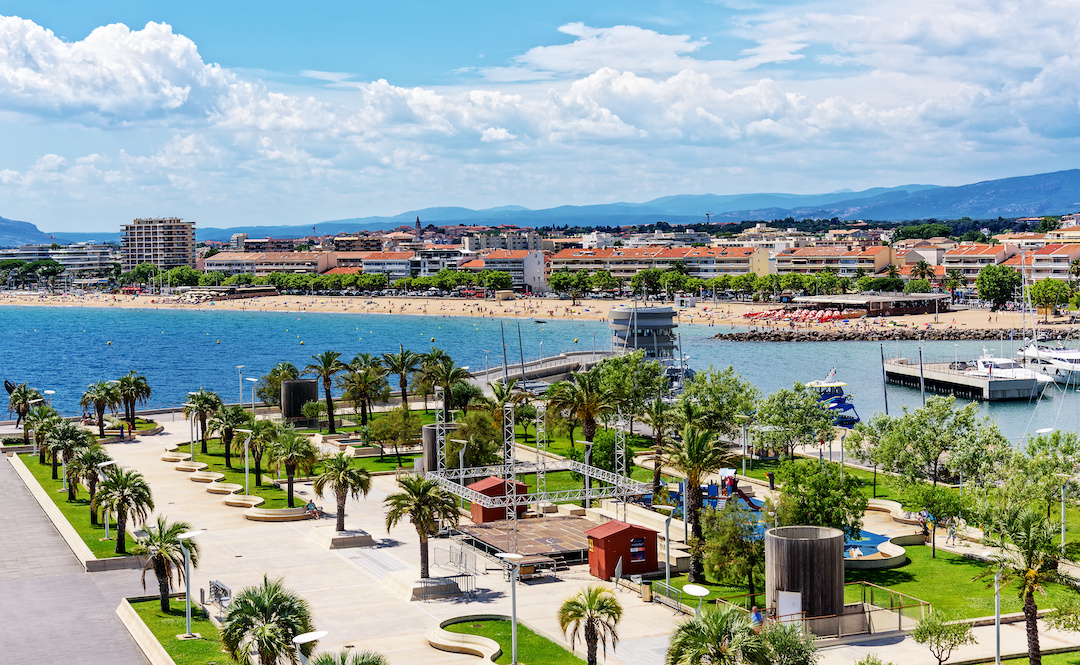
Whilst Fréjus remains more affordable, Saint-Raphaël is more upmarket, with prices for new-build properties at around €5,100 per m² or even higher for certain developments, depending on the standard of finish, and still offering good potential for capital appreciation. As some areas are already quite densely built-up, it is important to be selective.
Located within the municipality of Saint-Raphaël, the seaside resort of Agay has gained significant momentum in recent years, establishing itself as an elegant coastal village set within a highly protected natural environment. It is unlikely to evolve into a high-energy Riviera destination—but that is precisely part of its appeal. Its more preserved, family-oriented, and nature-focused positioning resonates strongly with buyers seeking a quieter interpretation of the Côte d’Azur lifestyle. Here too, new-build inventory remains limited, with pricing generally ranging between €6,000 and €8,000 per square metre. That said, select new residential developments remain available from approximately €6,500 per square metre (excluding optional upgrades and parking allocations).
GULF OF SAINT-TROPEZ: AN ULTRA-DESIRABLE MICRO-MARKET
A natural jewel between land and sea, the Gulf of Saint-Tropez represents a unique case within the French Riviera property landscape: over the years, it has effectively evolved into a “mini international Riviera” in its own right.
Two distinct market profiles coexist here: on one side, Grimaud and Sainte-Maxime, two of the most resilient and desirable residential markets on the Côte d’Azur; on the other, Saint-Tropez itself, a highly specific international trophy market largely disconnected from fluctuations in domestic demand.
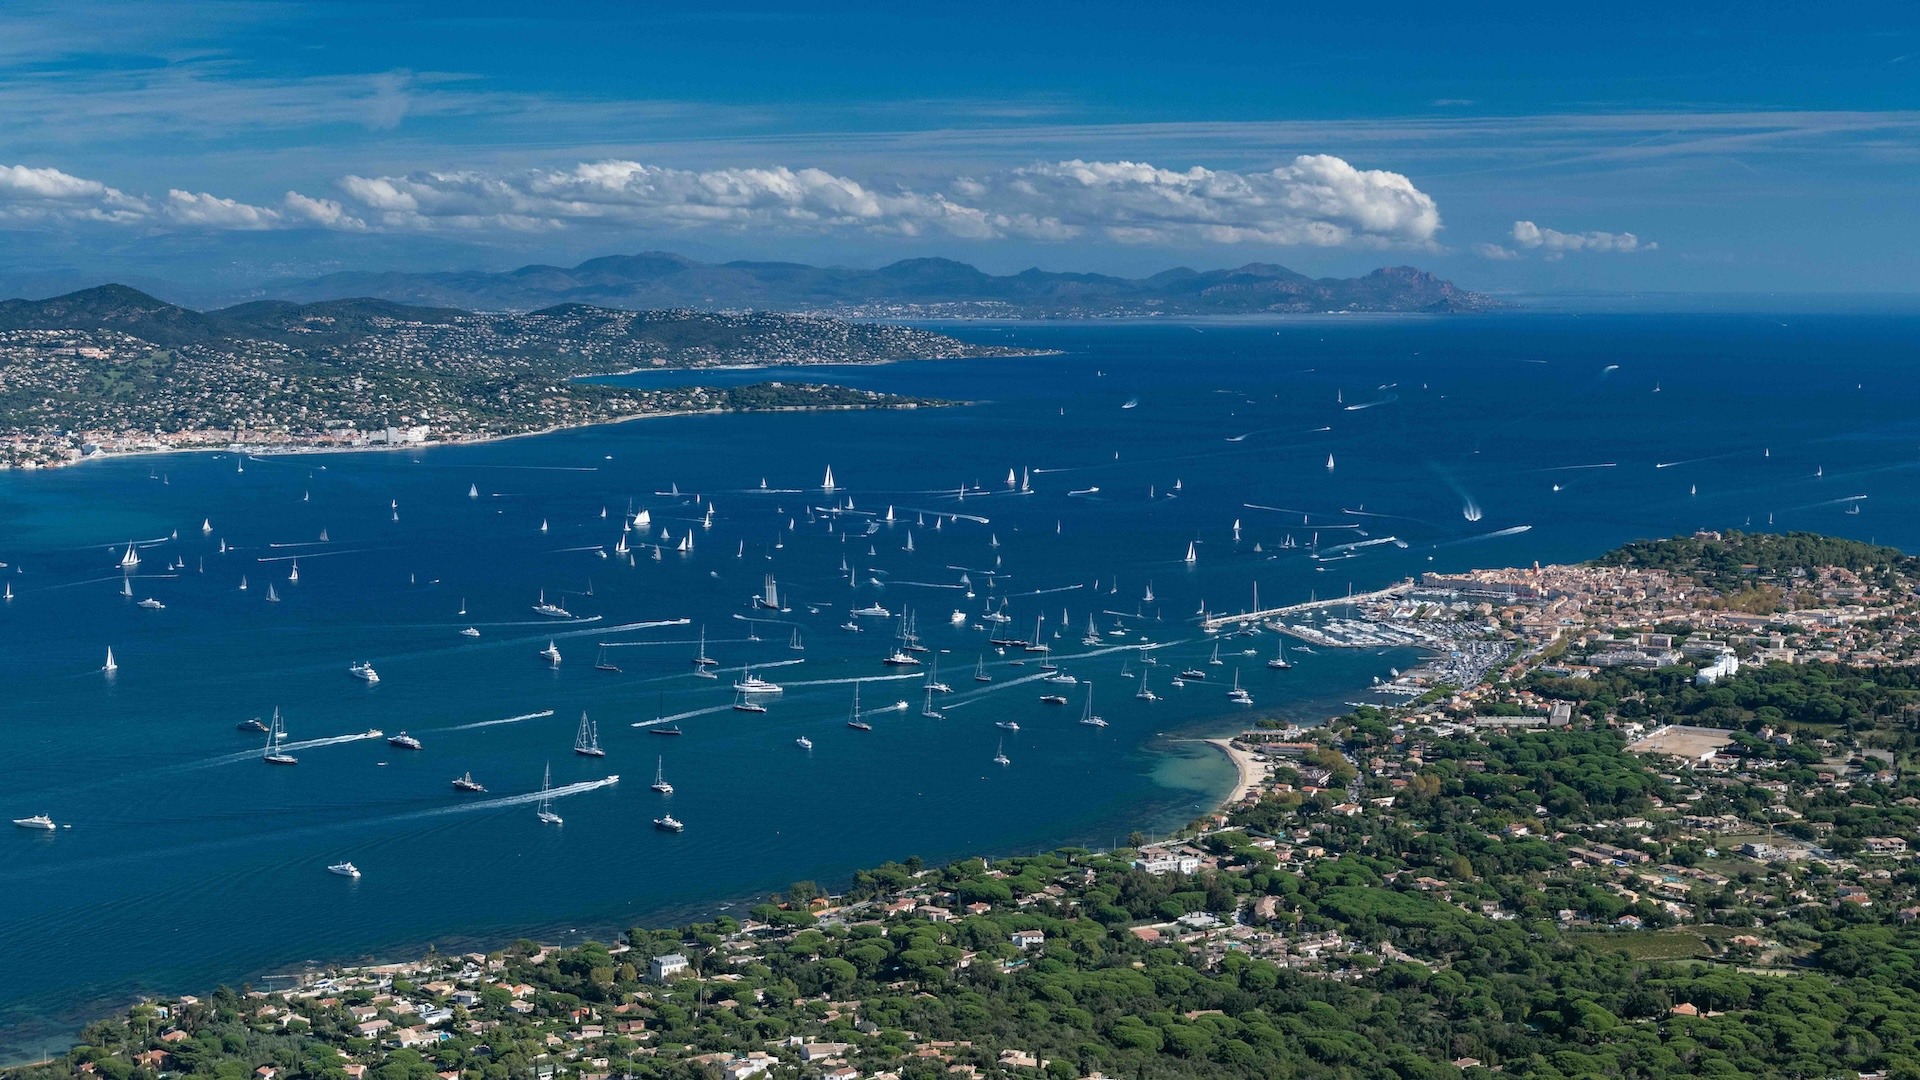
The seaside destinations of Grimaud and Sainte-Maxime present an ultra-desirable profile, with limited housing stock—and exceptionally scarce new-build inventory—attracting affluent French and international buyers alike. Crucially, they are far more liveable and residential than Saint-Tropez itself, the iconic jet-set village which, despite its global prestige, remains geographically constrained at the tip of a peninsula and notoriously difficult to access during the summer season. These structural advantages continue to underpin long-term price resilience.
A High-Performing Property Market
The Gulf of Saint-Tropez is not only a delight that captivates visitors with its beautiful scenery, but it has also been one of France’s best-performing property markets since 2020. In several towns, it is not uncommon to see cumulative price rises of between 20% and 40% since the start of the Covid pandemic. The value of certain properties (sea views, swimming pools, quiet surroundings, proximity to beaches) has skyrocketed.
This jewel of the Var coastline remains highly dynamic, yet fundamentally constrained by extreme land scarcity, strict planning regulations, and significant environmental restrictions. These structural pressures continue to drive capital values upward in the face of sustained demand.
Even properties not located in Saint-Tropez itself benefit from the global power of the Saint-Tropez “brand.” The area continues to attract entrepreneurs, liberal professionals, senior executives, and increasingly semi-mobile international buyers working remotely and spending several months per year in the region.
Within these micro-markets, however, product selectivity is essential. Hyper-local positioning makes a dramatic difference depending on sea views, orientation, beach accessibility, traffic exposure, summer nuisance factors, and topography. Two seemingly comparable properties may follow very different valuation trajectories.
The upper mid-market premium segment arguably offers the strongest risk-adjusted opportunity: new-build two-, three-, and four-bedroom apartments with sea views, often within residences featuring swimming pools, ideally located near both town centres and beaches.
This is particularly true in Sainte-Maxime, where appreciation potential, strong seasonal rental demand, and excellent market depth provide superior liquidity.
While premium family villas (sea views, swimming pool, land, peaceful surroundings) continue to offer compelling long-term upside due to finite supply and increasingly international demand, the ultra-luxury segment represents a more defensive but narrower market, highly dependent on global wealth flows.
In Grimaud, for example, certain hillside villas with panoramic views have effectively become international trophy assets, with pricing exceeding €15,000 per square metre.
Sainte-Maxime: A Premium Market in Full Rise
Sainte-Maxime has emerged as the Gulf’s leading premium residential market: liquid, balanced across different housing segments, and arguably the most genuinely liveable year-round.
A true four-season destination, it combines the infrastructure of a real town—shops, schools, year-round activity—with significant upgrading over the past two decades, attracting an increasingly diversified buyer profile.
Tourism growth has accelerated this momentum, with approximately 5 million overnight stays in 2025, supported by seven sandy beaches and fast ferry shuttles reaching Saint-Tropez in just 15 minutes, avoiding the severe road congestion typical during peak season.
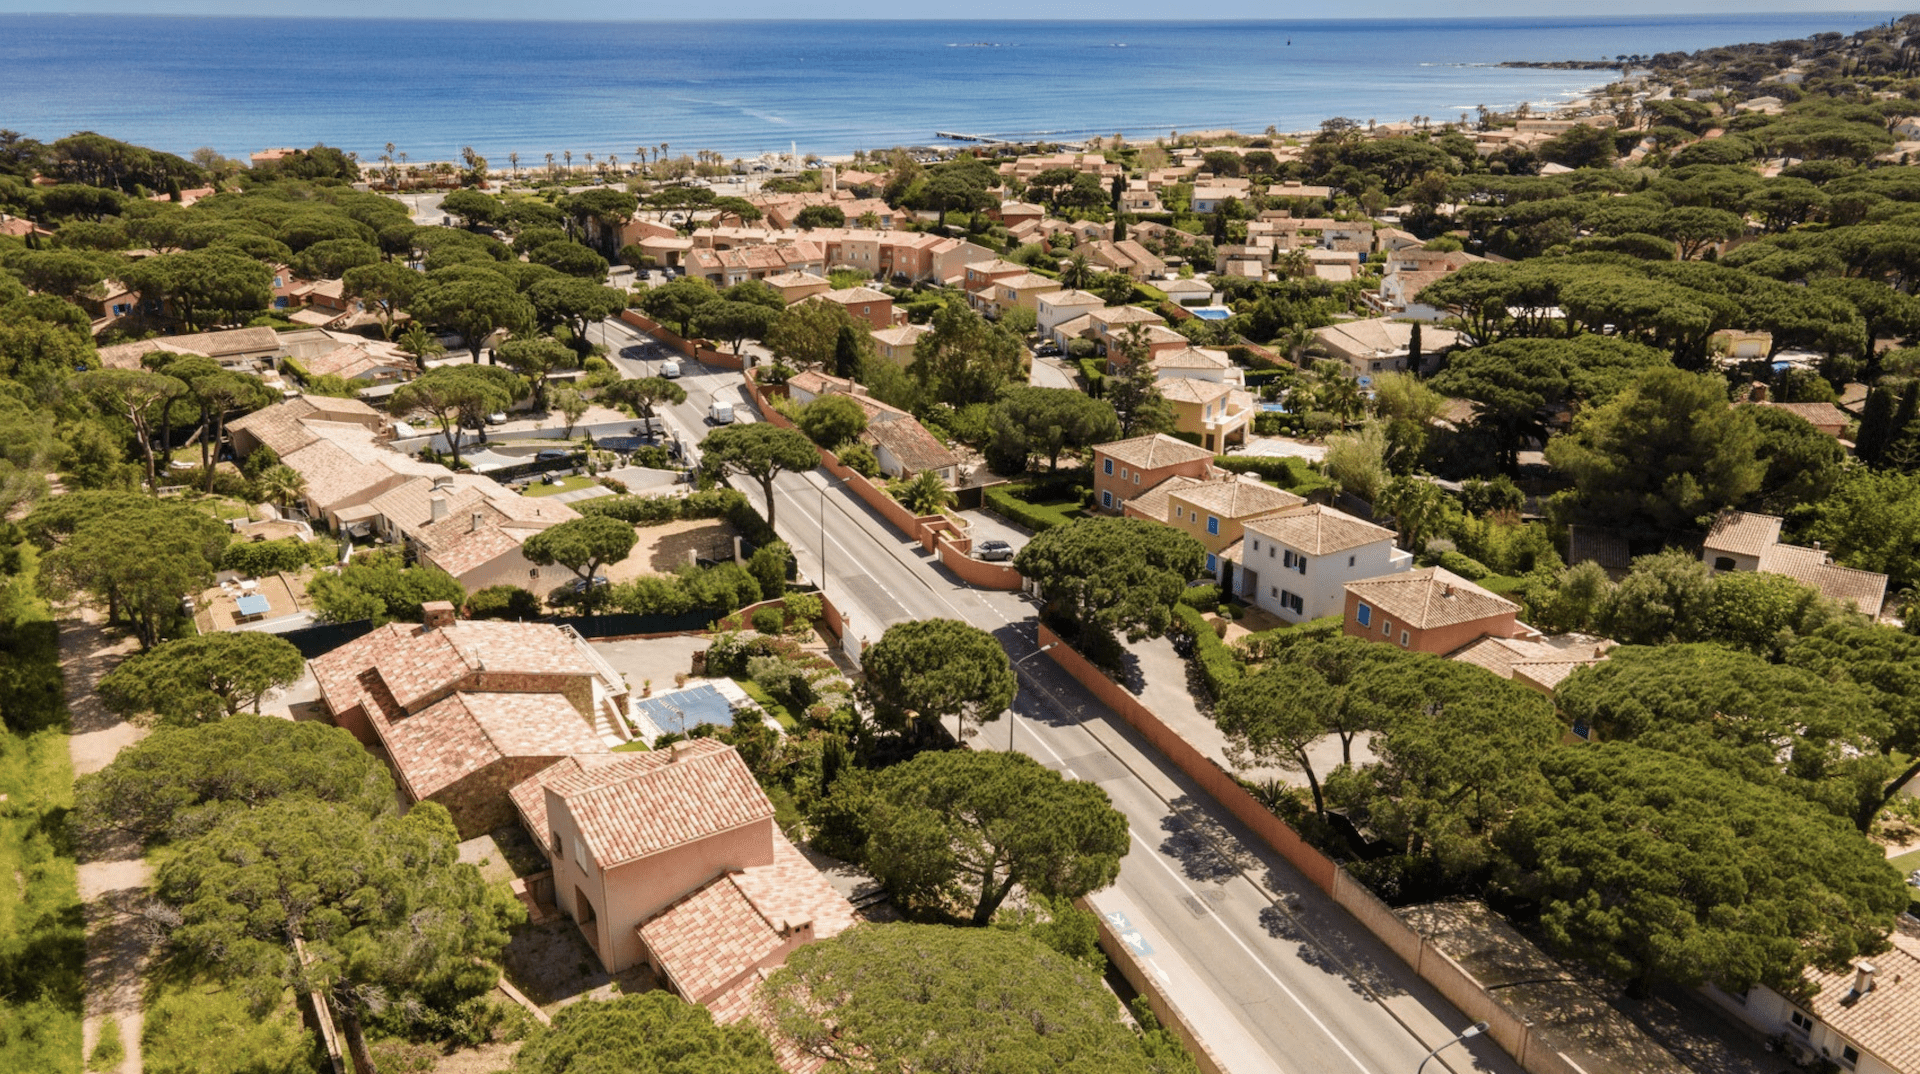
Sainte-Maxime now attracts affluent retirees, semi-residents, families, buyers from Lyon and Paris, as well as a discreet international clientele less ostentatious than that found in Cannes or Monaco.
Its exceptional quality of life, Mediterranean climate, sea-view positioning—whether beachfront or from surrounding hillsides—and the near impossibility of creating significant new supply have made it one of the Gulf’s most sought-after addresses.
More accessible than Saint-Tropez, yet without many of its practical drawbacks, Sainte-Maxime supports a residential market steadily moving further upmarket, particularly in the prestige and luxury segments.
Average property prices have increased by approximately 27% to 34% over the past five years.
Today, prices for new-build properties range from €7,000 to €10,000 per square metre, and even higher for premium properties with sea views – between €11,000 and €15,000 per square metre – particularly those on the seafront or in exclusive neighbourhoods near the beaches of La Nartelle and La Croisette.
Grimaud, a more exclusive proposition
More exclusive in profile, Grimaud has positioned itself as a distinctly “premium Provençal” market—narrower and less liquid than Sainte-Maxime, yet highly sought after by affluent French buyers and a very international clientele including Belgians, Dutch, Swiss, and British purchasers.
Its appeal lies in undeniable charm, preserved natural surroundings, exceptionally low-density residential development, and villas enjoying spectacular elevated views over the Gulf—an increasingly rare combination on the Côte d’Azur.
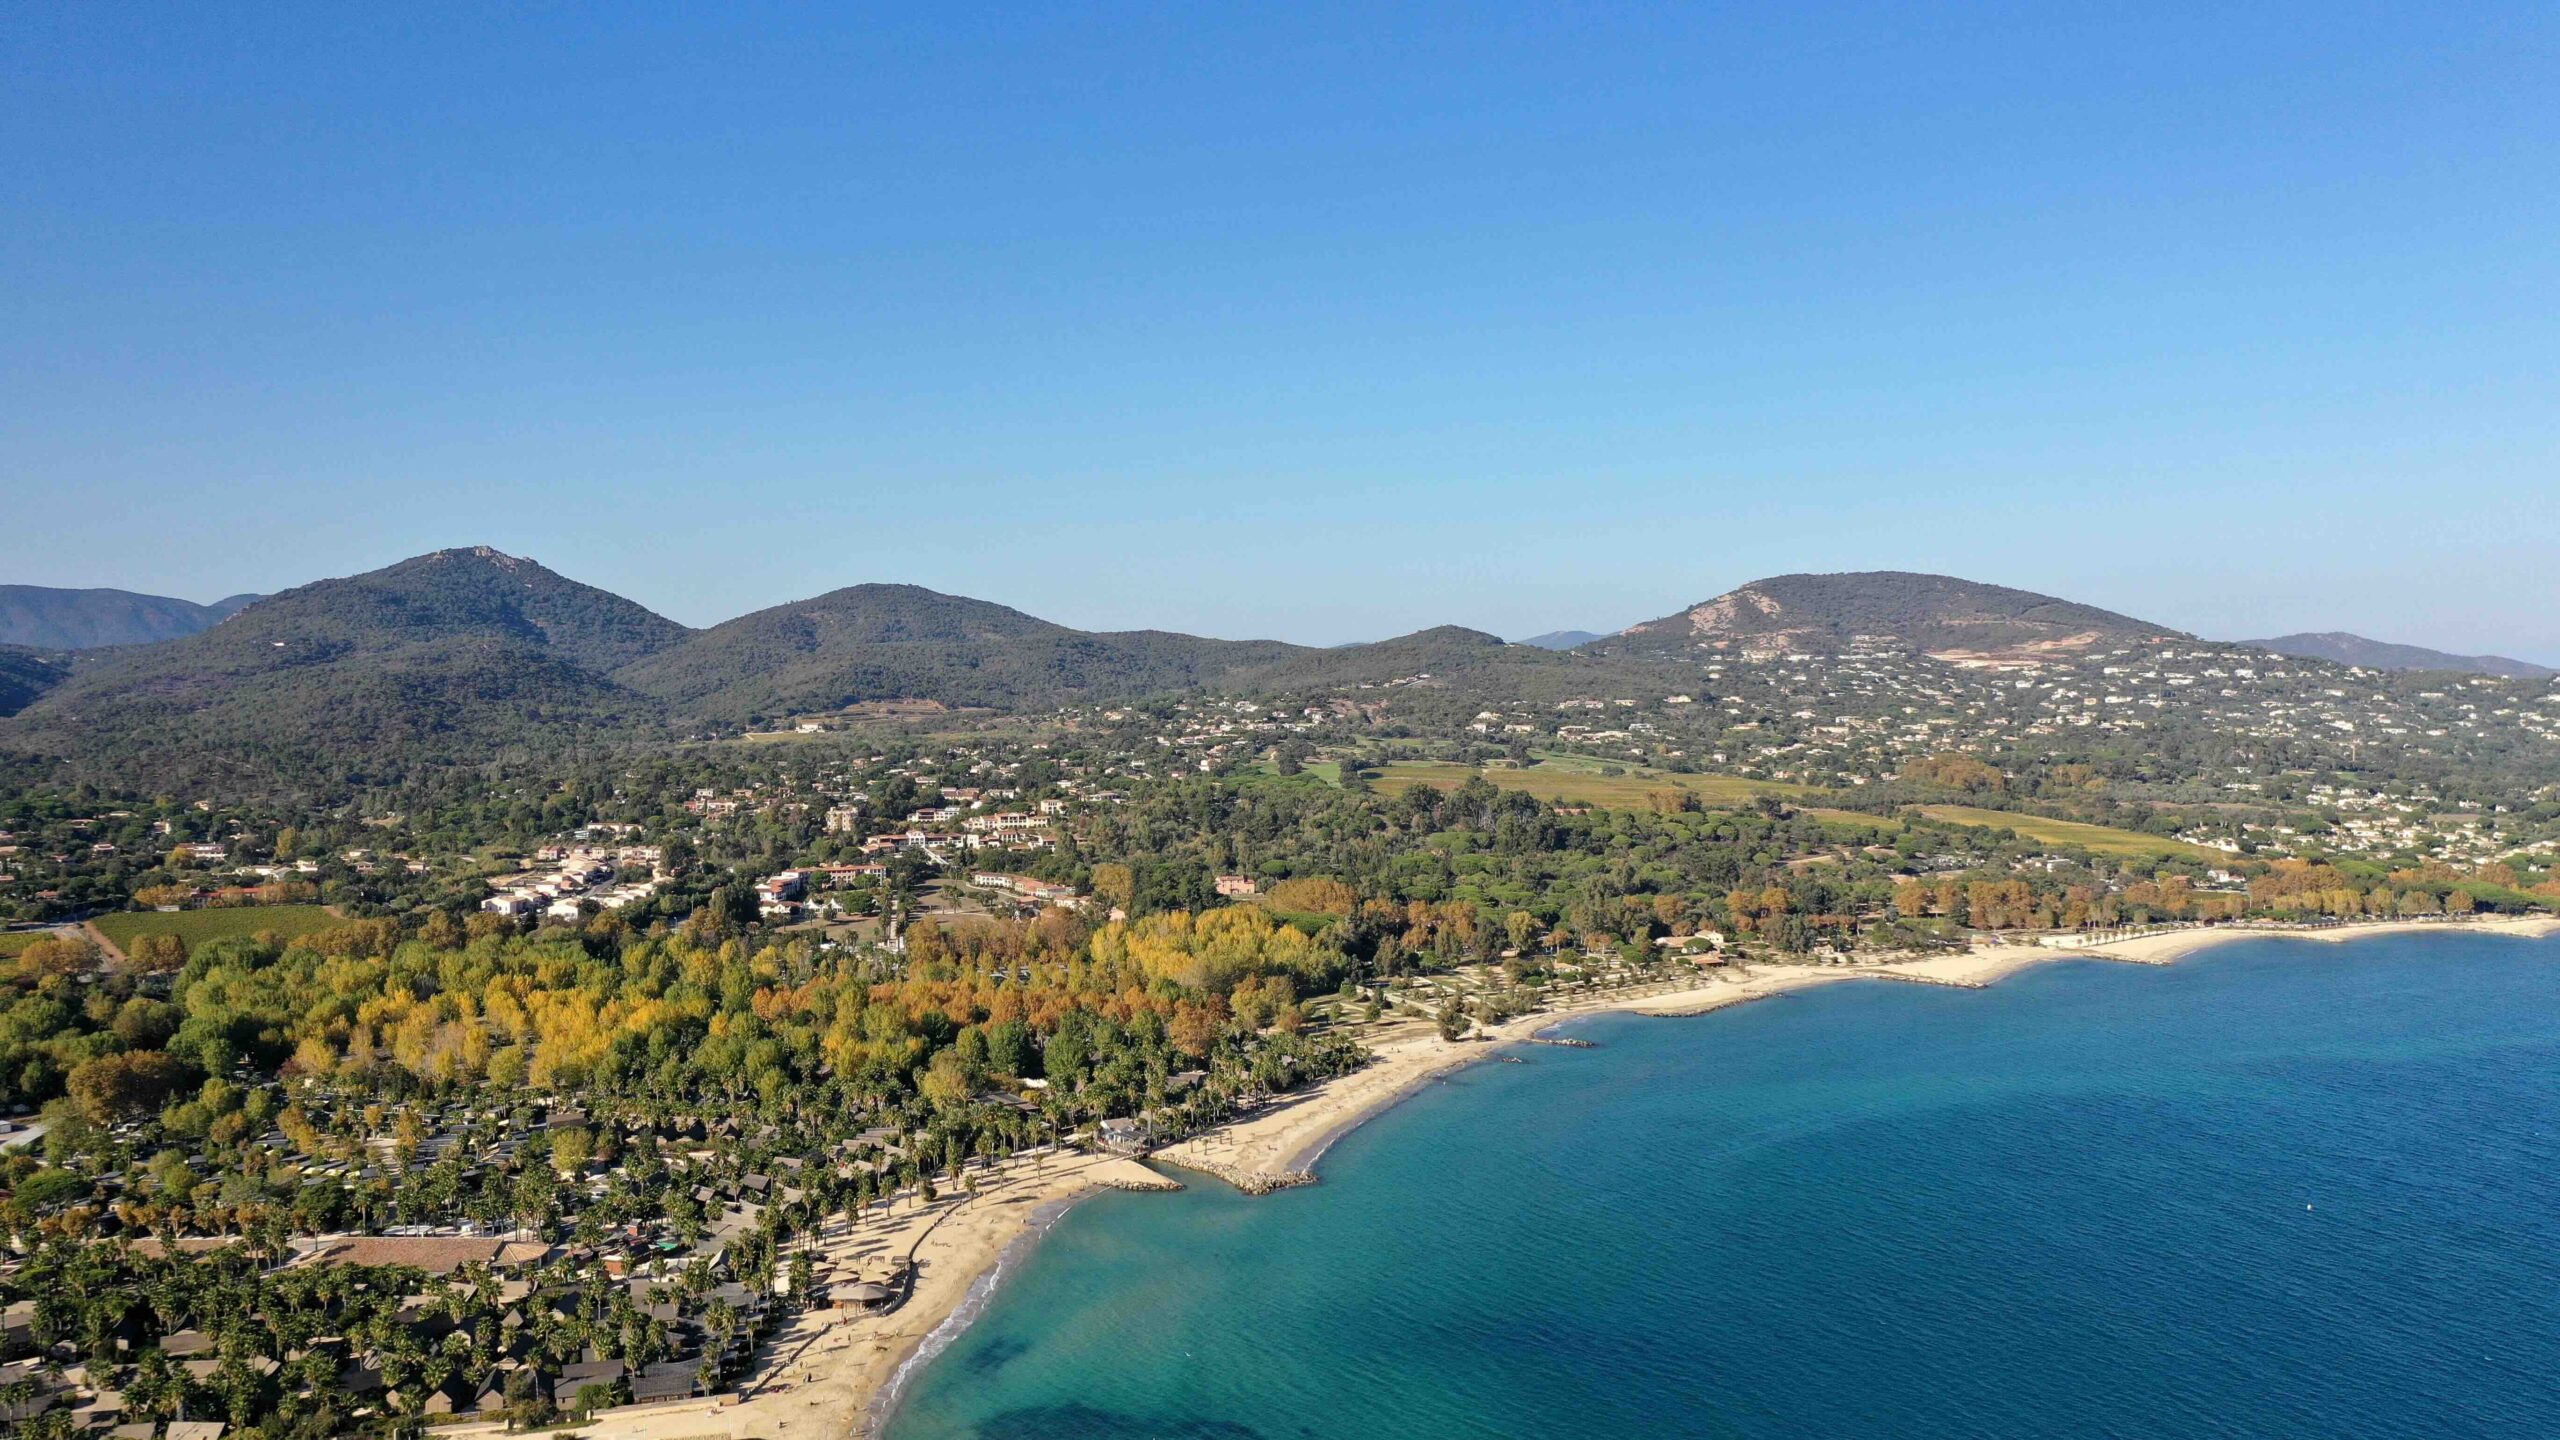
This ‘premium heritage’ property market, which is benefiting from the Saint-Tropez spillover effect, is driving prices upwards. It is one of the Côte d’Azur markets that has seen the sharpest rise in prices – between 33 and 44% over five years (2020–2025), which is enormous, even by Côte d’Azur standards, although there has been some consolidation recently.
This strong demand is buoying the new-build property market, with prices ranging from €7,000 to €9,000 per m², a median price of around €7,600 per m², and up to €10,000 to €12,000 per m² for premium properties. In residential hillside areas, such as the Beauvallon Bartole private estate, prices for luxury villas with swimming pools and spectacular views over the Gulf of Saint-Tropez can range from €14,000 to €17,000 per m².
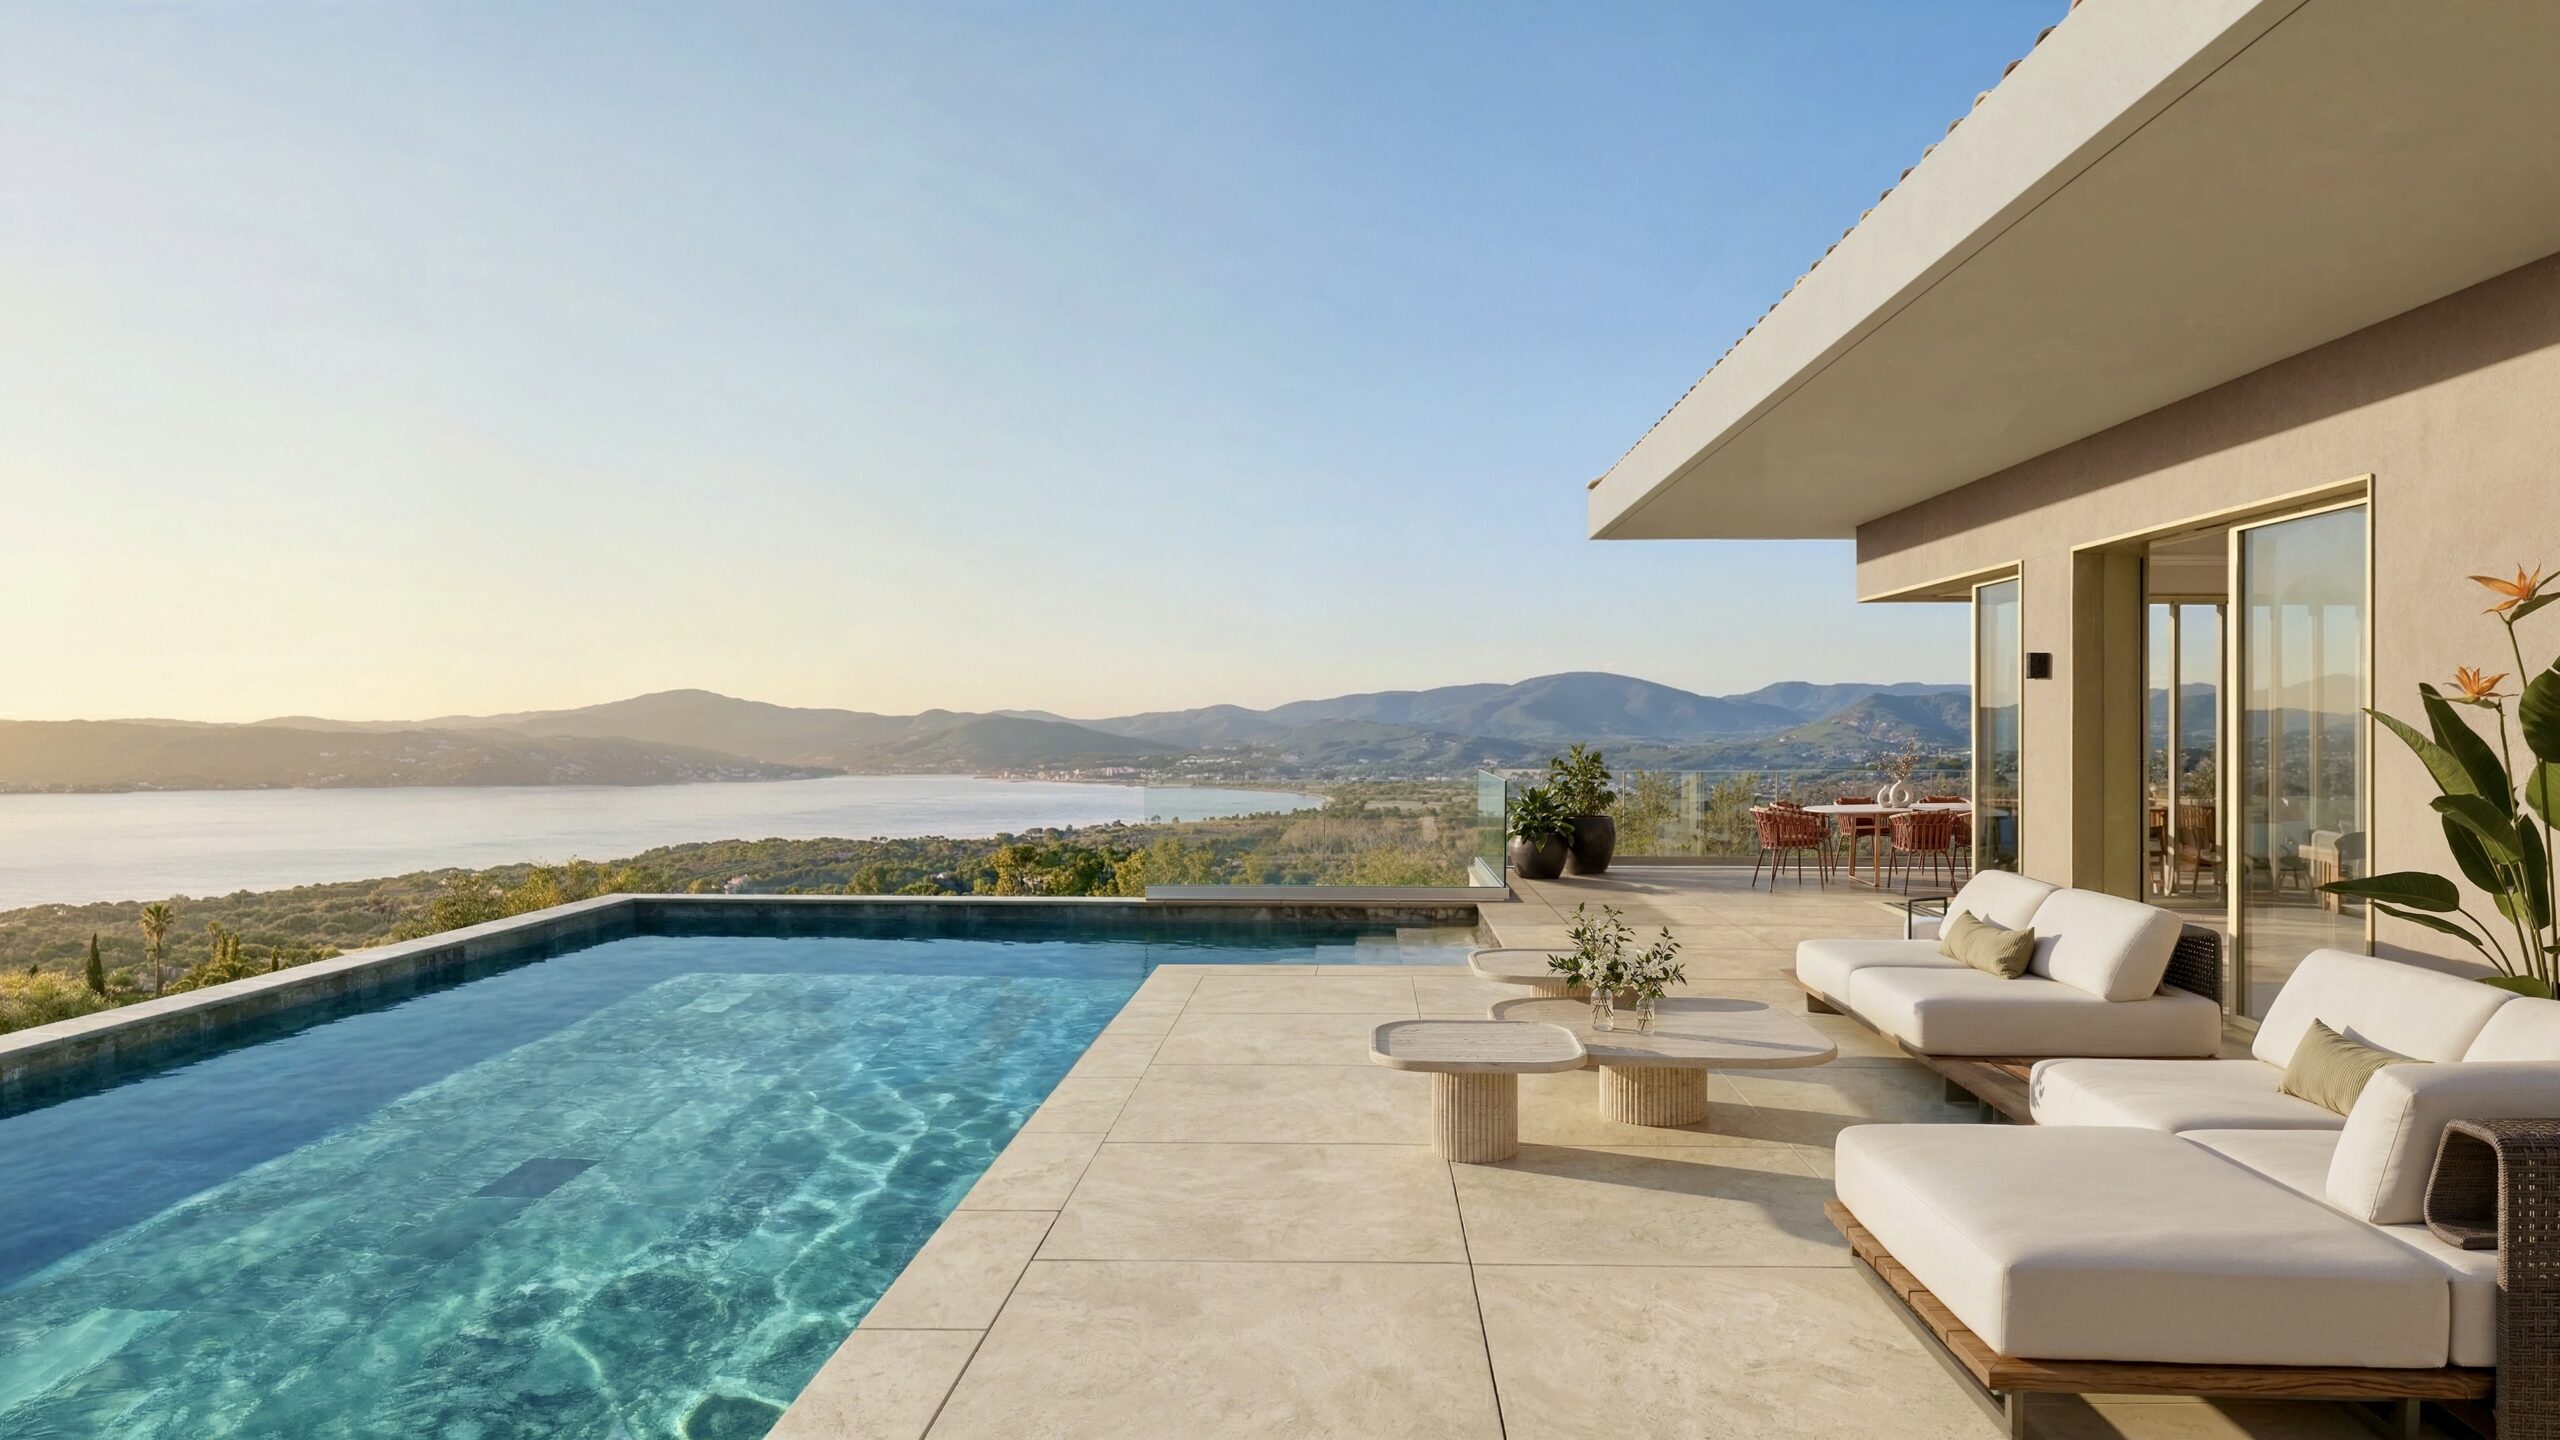
Port Grimaud represents an entirely separate niche: a real estate product unlike any other in Europe.
Driven by boating enthusiasts and international lifestyle buyers seeking canal-front living with private moorings and direct boat access, this very specific segment remains highly attractive—although ownership comes with elevated maintenance costs and variable liquidity depending on the precise asset.
Saint-Tropez: a global trophy address
The former fishing village ofSaint-Tropez has undergone a remarkable transformation since the 1950s.
Now functioning as a globally recognised lifestyle destination comparable to Monaco, Capri, Ibiza, or select districts of Miami, Saint-Tropez operates less as a traditional local housing market and more as an international trophy asset ecosystem.
Here, asset value is underpinned by extreme scarcity, global prestige, and ultra-premium specifications.
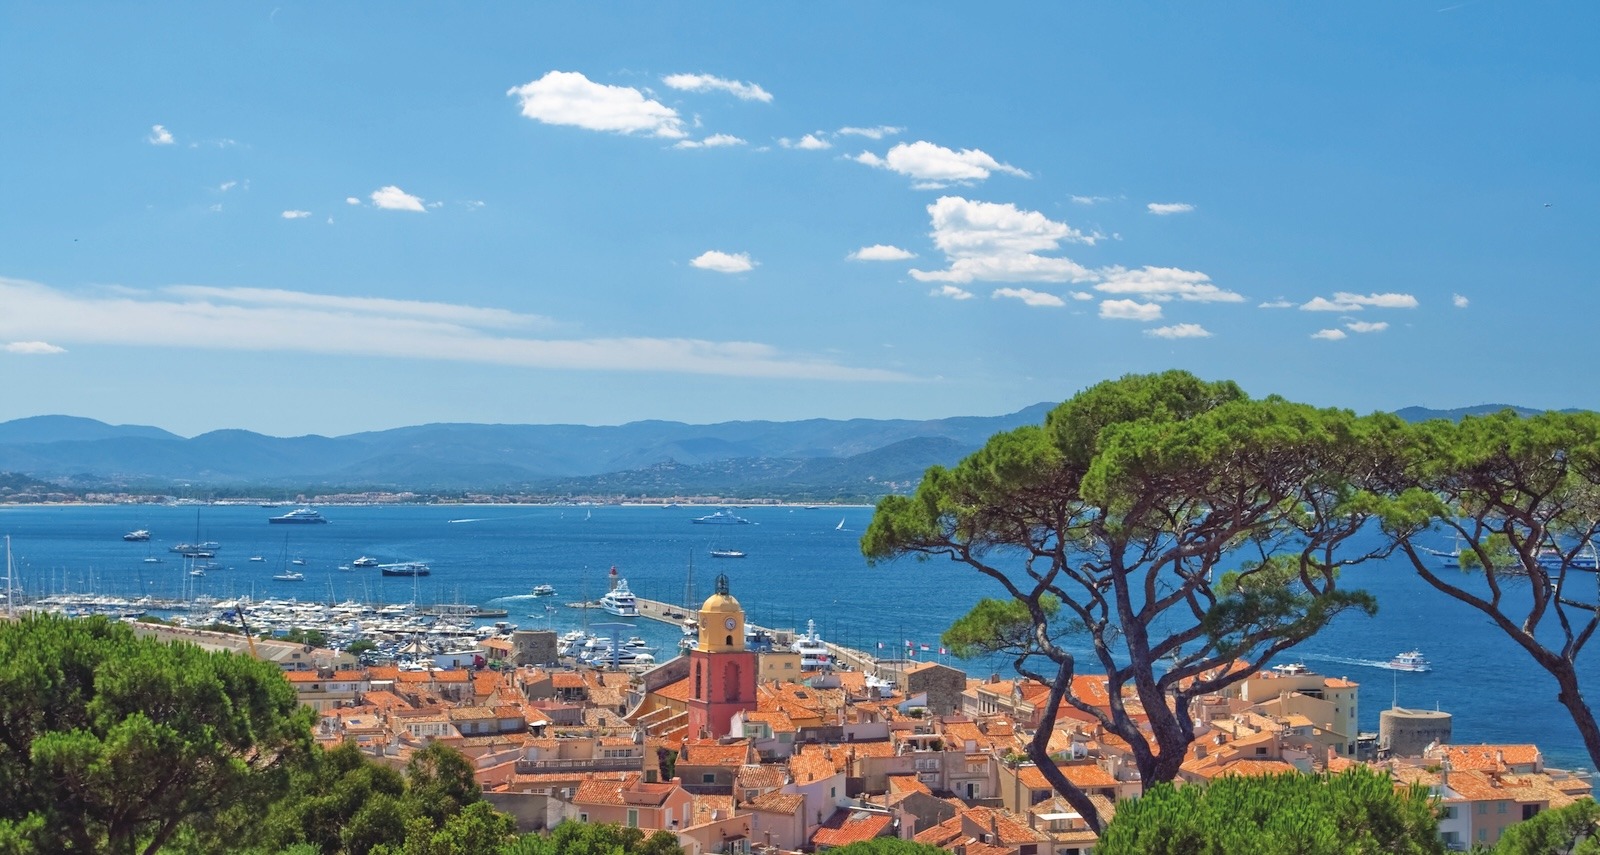
Here, asset value is underpinned by extreme scarcity, global prestige, and ultra-premium specifications.
Traditional market constraints—interest rates, taxation, domestic economic cycles—carry relatively little weight for its buyer base: global UHNW (ultra-high net worth) individuals, European and Middle Eastern wealth, American and Swiss entrepreneurs, celebrities, and family offices.
As a result, upside potential is naturally more limited, as much of the prestige premium is already priced in.
New-build developments are extremely rare here. This scarcity drives prices per m² to among the highest in France. For example, the Patio Ruben new-build development – an intimate residence comprising just six flats in the heart of the village, a stone’s throw from the famous Place des Lices and the beaches – offers exceptional flats with terraces and gardens at around €29,000 per m² (excluding garages or parking spaces).
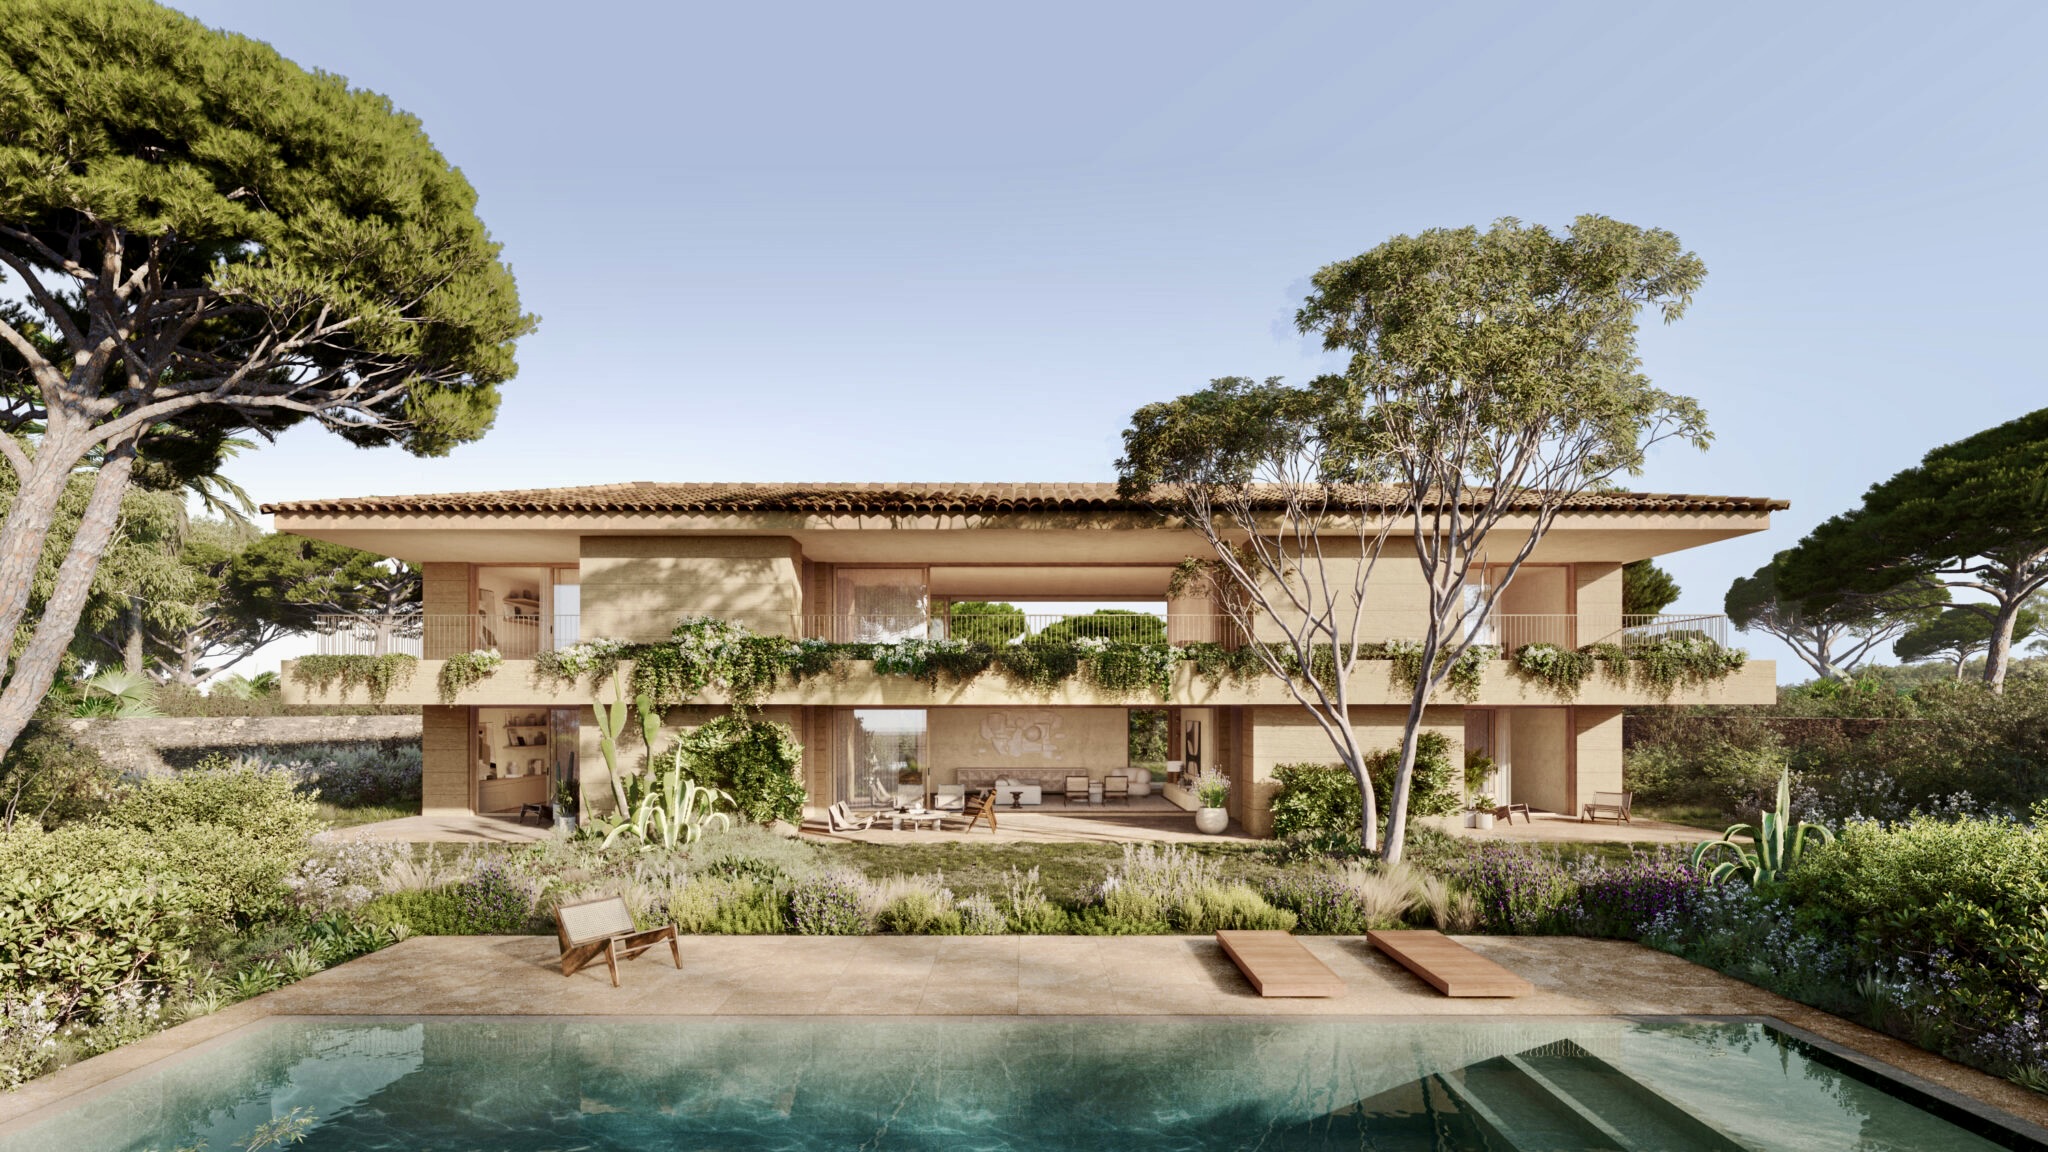
Immediately south of Saint-Tropez, Ramatuelle is often even more coveted, offering greater privacy, larger estates, lower density, preserved natural surroundings, and access to the legendary Pampelonne beaches.
Extreme scarcity, highly discreet transactions (with many villas trading off-market), and strong international wealth demand make this an ultra-premium, highly illiquid segment where pricing dispersion can be dramatic depending on sea views, beach proximity, land size, and extension potential.
Exceptional trophy properties may require months — or even years — to transact, simply due to their rarity and price point.
Further east and inland, Cogolin offers a more residential and affordable option for a ‘rational’ investor. Benefiting from the spillover from Saint-Tropez and Sainte-Maxime, significantly lower prices and an active clientele, it offers a genuine year-round lifestyle right on the Gulf. Prices there have been rising for several years, particularly in the premium segments, whilst remaining affordable.
Translated with DeepL.com (free version)
BOUCHES-DU-RHÔNE: FROM THE CALANQUES TO LA CIOTAT
And what about the Bouches-du-Rhône, you might ask ? If, as some people do, one considers that the Côte d’Azur begins just beyond Marseille, the stretch of coastline running from the Calanques mountains to La Ciotat and Cap Sicié also offers some excellent opportunities for property investment.
A world-famous village, Cassis is often described as a ‘miniature Saint-Tropez’, a destination favoured by affluent French and international visitors. Prices for new-build properties are already high, with average prices ranging from €7,500 to €10,000 per square metre, and the property market is performing very strongly, thanks to a very robust market, partly due to the scarcity of land available.
De son côté, La Ciotat continue d’offrir l’un des marchés les plus solides du littoral azuréen. Fort de ses atouts – un littoral très recherché, une économie dynamique avec les chantiers navals et la technopôle de l’Arbois/Marseille, une forte attractivité pour les retraités et les résidences secondaires, un cadre de vie supérieur aux communes voisines – La Ciotat a connu une flambée des prix du neuf ces cinq dernières années (+14 à 30%).
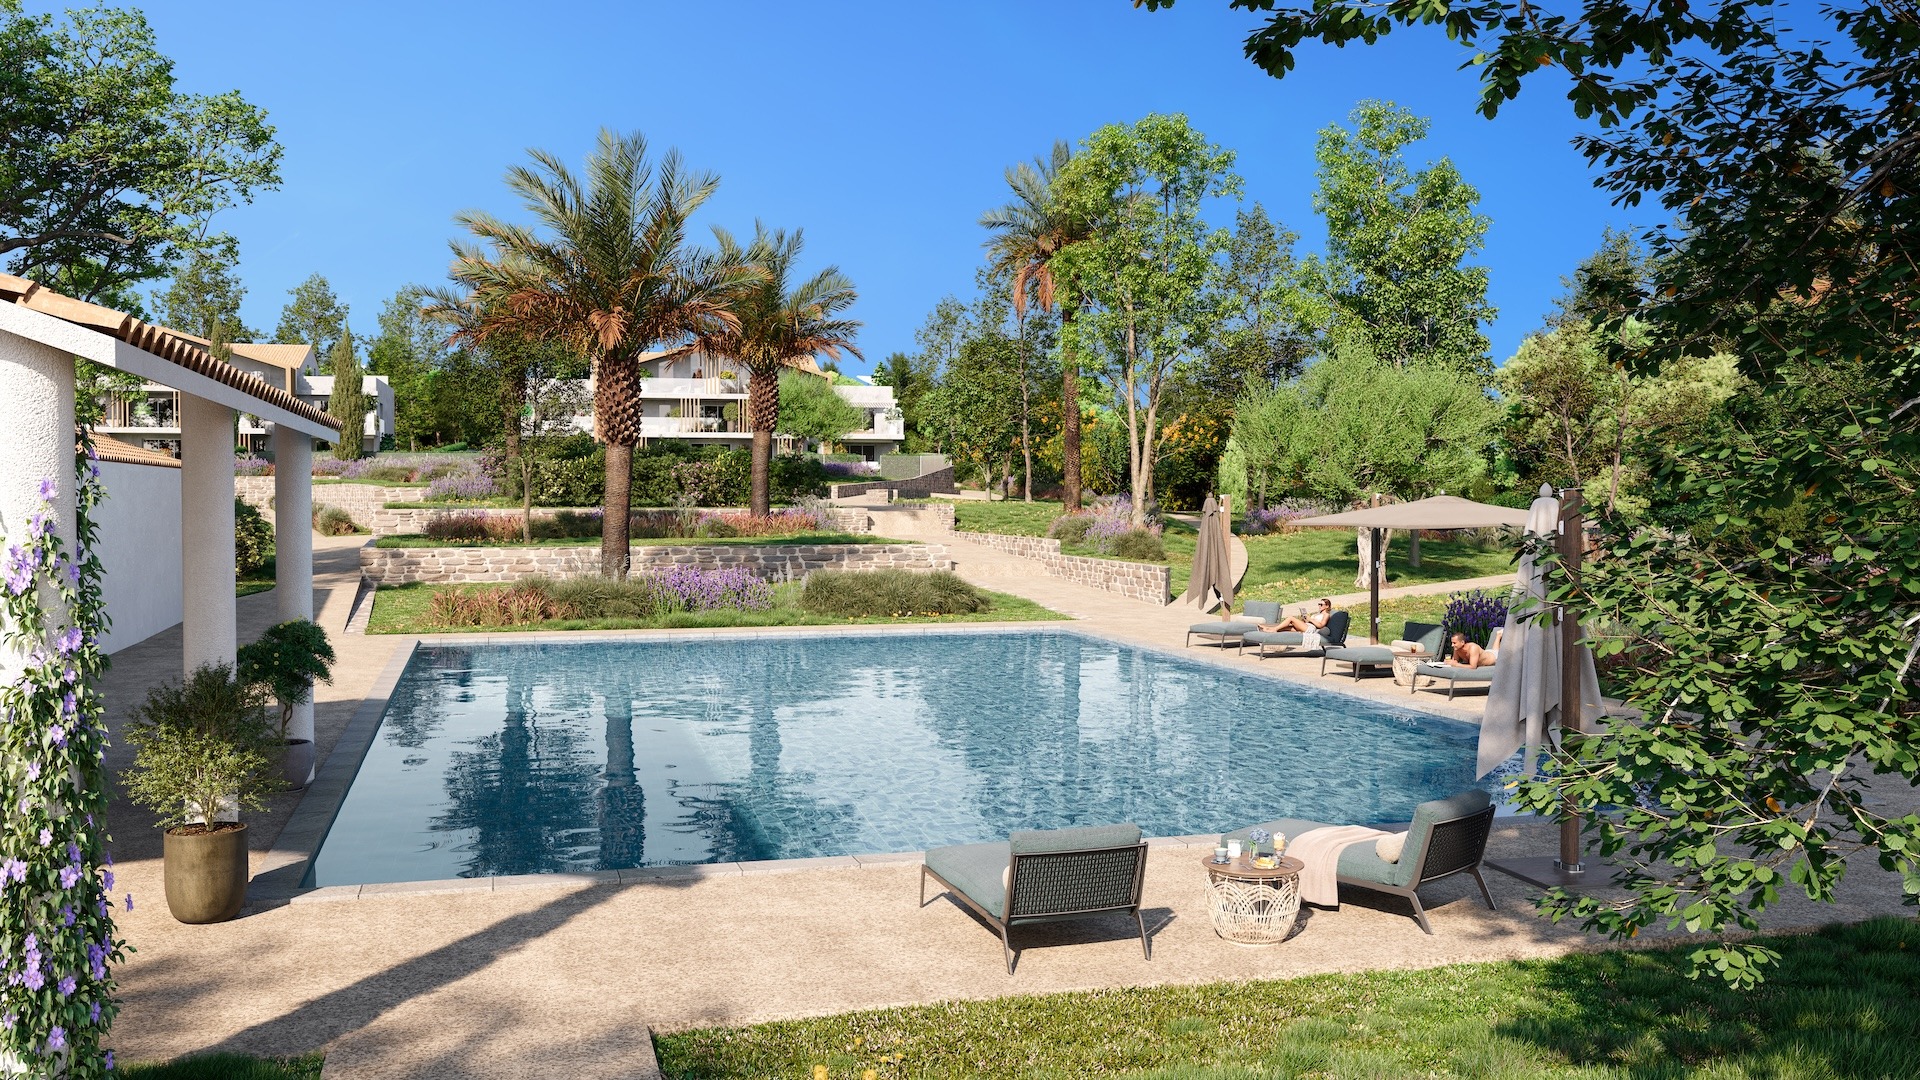
New-build developments in La Ciotat are rare and are priced between €7,000 and €10,000 per m2, depending on the standard of the property, representing a premium of 30 to 70% for new-builds compared with older properties; this is justified by the standard of fittings and comfort, as well as energy and environmental performance. A prime example is the new Le Domaine du Baguier residential development.
COASTLINE OR HINTERLAND: WHICH INVESTMENT STRATEGY TO PRIORITISE ?
When it comes to new-build real estate, the Riviera and Var hinterland—comprising villages located 20 to 30 kilometres inland from the coastline—was long considered a secondary market. That is no longer the case. Over the past two decades, these areas have emerged as a major investment theme in their own right, supported by several powerful structural trends that continue to sustain both demand and long-term capital values.
The first driver is the relentless price inflation along the coastline. Buyers who can no longer access markets such as Nice, Cannes, Antibes or Saint-Raphaël increasingly shift their focus towards inland alternatives including Vence, Valbonne, Mougins, Grasse and its surrounding areas, Fayence, Le Rouret, Tourrettes, and similar locations.
The second is the search for an improved quality of life. Greater space, private gardens, detached homes, and a more peaceful environment are significantly more attainable away from the coast. The rise of remote and hybrid working has also profoundly reshaped buyer geography, with many executives now willing to commute two or three days per week in exchange for superior lifestyle conditions—particularly when escaping the chronic traffic congestion of the Riviera.
The third factor is the structural scarcity of supply in the most attractive villages. In many municipalities, available land is now extremely limited, while strict local planning frameworks and environmental preservation policies severely restrict future development. As a result, new-build supply remains exceptionally scarce, underpinning long-term price resilience.
Broadly speaking, three distinct categories emerge: the connected hinterland, the residential hinterland, and more isolated rural markets where long-term capital preservation and appreciation prospects remain significantly weaker..
The Nice Hinterland: A Highly Defensive Market
The Nice hinterland remains particularly sought after by international buyers, affluent retirees, remote professionals, and semi-resident owners—especially within highly connected, upscale villages such as Vence, Saint-Paul-de-Vence, and La Colle-sur-Loup.
Their appeal is obvious: exceptional natural surroundings, authentic Provençal character, and proximity to Nice International Airport—factors that continue to support strong long-term capital appreciation, albeit from already elevated pricing levels.
Less glamorous but equally authentic, more residential villages such as Carros, Gattières, and Levens increasingly benefit from a spillover effect from Nice.
These areas remain more accessible, making them attractive to families, working professionals, and first-time buyers. However, performance remains highly dependent on commuting times, transport infrastructure, and the intrinsic quality of each village.
The Cannes Hinterland: One of the Strongest Long-Term Bets
Located just seven kilometres from Cannes, Mougins has effectively become a defensive “safe-haven” asset within the Riviera market. Indeed, it now functions as a globally recognised premium residential market, highly sought after by entrepreneurs, international buyers, and affluent families
Its advantages are clear: immediate proximity to Cannes and the coastline, international schools, security, and consistently high-quality real estate stock, often with exceptional specifications. The only obvious limitation to future appreciation is the fact that values are already relatively high.
New-build pricing in Mougins typically ranges between €4,500 and €7,000 per square metre for quality residential apartments, while premium and luxury villas with poolgenerally command €8,000 to €11,000 per square metre, with landmark properties significantly exceeding these levels.
The countryside surrounding Sophia-Antipolis, with villages such as Valbonne, Mouans-Sartoux, Châteauneuf-Grasse, Opio and Roquefort-les-Pins, is arguably one of the region’s most robust areas. The reasons are clear, driven by the economic engine of Sophia-Antipolis: a huge pool of high-value-added tech jobs with high purchasing power, a highly affluent international population and high-quality international schools – all factors that underpin the market. Family villas, luxury residences—some of which are set in the countryside or on the edge of a golf course—and houses with outdoor spaces constitute the most sought-after segment and offer excellent long-term potential.

Across this entire sector, the supply of new-build properties remains very limited, but the value for money in terms of space remains very good.
The supply of new-build property developments in the area remains very limited due to the scarcity of land, as is the case in Opio and Châteauneuf-Grasse, with prices ranging from €5,500 to €7,500/m² for premium luxury residential developments, such as the new Eagle and Albatros residences, which offer views of the golf course, spacious outdoor areas and high-end amenities.
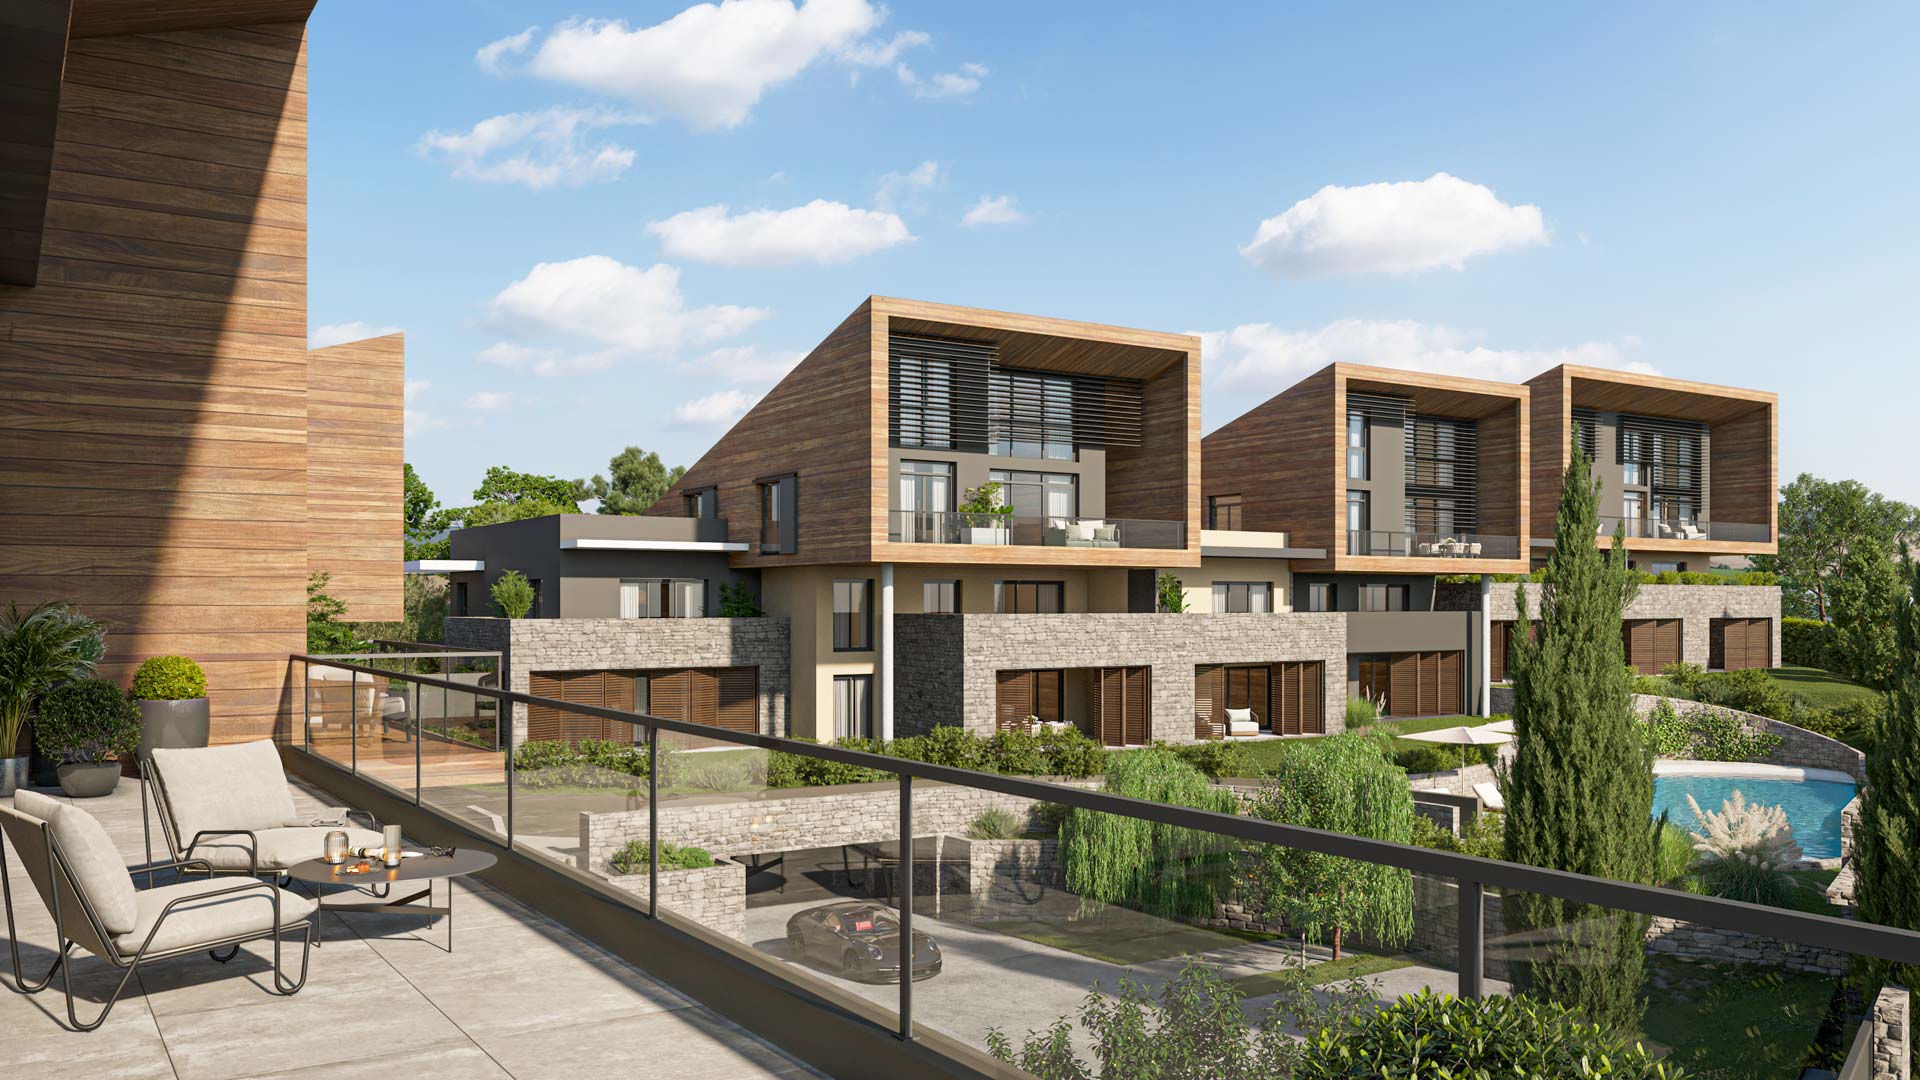
Valbonne and Mouans-Sartoux, in particular, benefit from exceptional residential depth and liquidity, driven by sustained family demand seeking the ideal balance between quality of life, schools, daily convenience, and fast access to Sophia Antipolis.
Long regarded as one of the less attractive addresses on the Côte d’Azur — burdened by quality-of-life concerns, security perceptions, and accessibility issues — Grasse, despite its UNESCO World Heritage status, has begun repositioning itself. Infrastructure improvements, including enhanced road connectivity to Sophia Antipolis and Cannes, alongside the gradual reduction of historic industrial nuisances, are beginning to attract higher-income demographics. As residential supply improves, Grasse may offer one of the region’s more compelling catch-up stories over the next 10 to 15 years. That said, this remains a highly neighbourhood-sensitive market where selectivity is critical.
The Var Hinterland : Significant Upmarket Momentum
A similar transformation is underway across the Var hinterland, where significant upgrading has taken place in recent years. Around Lac de Saint-Cassien, villages such as Fayence, Tourrettes, Callian, and Lorgues arguably offer some of the most attractive potential value-to-price ratios in southern France.
International buyers are drawn by the authenticity of these villages, gastronomic appeal, larger plots, premium villas with land, nearby golf courses, and relative proximity to the coast—all at pricing materially below prime waterfront locations.
By contrast, Draguignan represents a more rational, less lifestyle-driven investment proposition. Less glamorous and less patrimonial in nature, it nevertheless benefits from a sufficiently robust local residential base to support stronger rental yields, particularly within renovated districts.
Selectivity Remains Essential
Successful property investment in the hinterland requires discipline and granular market understanding.
Two villages separated by only five kilometres may exhibit completely different buyer profiles, school quality, liquidity characteristics, and long-term resilience. Most importantly, commuting time remains decisive. Once travel times exceed approximately 40 to 45 minutes from major employment hubs, market fragility increases significantly.
We can therefore distinguish between areas with very high potential for capital appreciation (Valbonne, Châteauneuf-Grasse, Opio, Mouans-Sartoux, residential Grasse, Fayence, Tourrettes) and others that offer a very secure investment, such as Mougins, Saint-Paul-de-Vence, Vence, premium Valbonne, etc. Finally, for those with a taste for risk, more speculative but potentially high-growth areas could be considered, such as certain parts of Grasse, residential Carros, the redeveloped area of Draguignan and certain villages undergoing transformation.
The “Connected Hinterland”: The Optimal Compromise
For buyers priced out of the Riviera coastline — or simply seeking to escape its saturation — the connected hinterland arguably represents the most compelling strategic compromise on the Côte d’Azur.
MoinLess expensive than the premium coastal areas, it offers significant potential for capital appreciation due to strong underlying demand, a quality of life that remains exceptional, and the scarcity of land – all factors that help maintain property values. The most promising areas in the long term are Valbonne, Opio, Roquefort-les-Pins, Châteauneuf-Grasse, Mouans-Sartoux, Vence, Saint-Paul-de-Vence, Fayence, Tourrettes, and the hinterland near Toulon.
WHAT CAN YOU BUY — AND AT WHAT BUDGET ?
Budget remains, of course, the decisive question.
Naturally, everything depends on individual means, objectives, and lifestyle expectations. Yet—even if the notion of “affordability” remains relative in this context—the French Riviera still offers access points across virtually every budget bracket, from entry-level residential assets to globally positioned ultra-prime trophy properties.
A Lifestyle Dream at Multiple Price Points
The Côte d’Azur remains accessible across a broad range of budgets, particularly within the resale market, where pricing can still range from approximately €2,500 to €4,500 per square metre in selected locations.
However, the Riviera should never be approached as a single market, but rather as a mosaic of micro-markets, each with its own pricing logic, demand drivers, and long-term prospects.
For buyers operating within a “conventional” upper-middle-market budge — typically between €300,000 and €600,000 — ownership remains achievable, although not in every location, as certain prime sectors have become structurally inaccessible.
In the new-build property market, properties are scarcer due to rising land prices, planning and environmental restrictions, and increasing construction costs. They are therefore more expensive. On the other hand, new-build property developments can now represent a sound medium- to long-term investment because, in addition to all the advantages of new-build properties, they incorporate the latest standards in comfort and modernity (RE 2020): improved energy efficiency in houses and flats, high-quality materials, better natural light, optimised living space, and greater comfort in hot weather, etc.
New-build property on the Côte d’Azur frequently exceeds an average of €5,500/m², with prices in the Var slightly lower than in the Alpes-Maritimes. In the entry-level to mid-range segment, prices range from €3,500 to €5,000/m² in certain outlying areas or in urban regeneration projects within the aforementioned towns.
In the ‘mid-range’ luxury residential property segment, prices range on average from €5,500 to €9,000/m² (€7,200/m² in Nice, up 29% in five years), depending on the neighbourhood and additional factors (sea view, surroundings, etc.).
Enfin, dans le segment prestige/luxe, ils s’inscrivent dans une fourchette large, à partir de 10 000 €/m2 pour grimper jusqu’à 30 000 €/m2, voire au-delà pour des biens exceptionnels.
UReal Appreciation Potential — But Highly Variable
The strongest upside potential typically lies within the “emerging value” districts referenced earlier—areas undergoing structural transformation and progressive upgrading. Examples include parts of Eastern Nice, Saint-Roch, Riquier, and neighbourhoods benefiting from tramway extensions or future urban regeneration projects. These opportunities naturally involve a greater speculative element, but may also deliver the strongest capital appreciation.
Without question, the upper mid-market residential segment offers the most attractive ten-year risk-adjusted growth potential. It combines relatively low speculative risk, strong liquidity thanks to deep underlying market demand, and continued accessibility for affluent domestic and international buyers.
A well-positioned one-, two-, or three-bedroom apartment in Nice, Antibes, Beausoleil, or selected areas of the Cannes hinterland such as Châteauneuf-Grasse, remains a particularly sound strategy.
The combination of robust local and international demand, limited new supply, accessible pricing relative to buyer purchasing power, and favourable resale prospects creates compelling investment fundamentals.
TITRE A METTRE Prestige and Luxury: Capital Preservation First
The prestige and luxury segment offers extraordinary diversity, but follows a fundamentally different investment logic. Mediterranean luxury real estate increasingly behaves as an international capital-preservation asset rather than a vehicle for rapid speculative gains.
Buyers should, however, remain aware of the markedly different market dynamics. Entry tickets are substantially higher—typically beginning around €3 million—while market liquidity is far thinner, with fewer resale transactions and stronger dependence on global capital flows. Demand in this segment can also be influenced by geopolitical shifts, international wealth migration, and changing behavioural patterns among ultra-high-net-worth buyers (the Russians who had been flocking to the French Riviera since the 1990s have all but disappeared, and the super-rich oligarchs have completely abandoned Europe for fear of having their assets seized).
That said, entry into the prestige market does not require billionaire status.
A quality sea-view apartment in Sainte-Maxime remains accessible from approximately €799,000, while a contemporary prestige villa with swimming pool in the Cannes hinterland — Mougins, for example — may begin around €1.58 million.
TITRE EN GRAS Why the Var May Offer the Best Strategic Value
For long-term investors, buyers operating with intermediate budgets, or those genuinely seeking meaningful capital appreciation rather than pure wealth preservation, the Var arguably offers the strongest overall investment proposition.
Its combination of relative affordability, strong structural demand, scarcity dynamics, lifestyle appeal, and further room for market maturation creates a particularly compelling risk/reward profile.
WHERE THE SUN RISES… IN THE SOUTH !
Ultimately, the Côte d’Azur remains one of France’s most diverse, most desirable, and arguably most resilient real estate markets. Its enduring strength lies in a rare convergence of powerful fundamentals: exceptional climate, international appeal, constrained supply, enduring lifestyle desirability, and sustained global demand.
Yes, prices on the Côte d’Azur are higher than almost anywhere else in France—Paris aside. And they are likely to remain so. After all, sunshine has no price.
And on the French Riviera, as we all know, the sun rises… in the south.
Naturally, location selection must align with individual objectives—whether primary residence, second home, seasonal rental investment, or long-term capital appreciation strategy. Budget, lifestyle aspirations, and investment philosophy will determine whether one prioritises wealth preservation or growth potential; coastline or hinterland; prestige or practicality.
Yes, prices on the Côte d’Azur are higher than almost anywhere else in France — Paris aside. And they are likely to remain so. After all, sunshine has no price.
And on the French Riviera, the sun rises… in the south.